Federal Court of Australia
Kingmill Pty Ltd v Darwin International Airport Pty Ltd [2026] FCA 1747
File number: | NTD 20 of 2025 |
Judgment of: | CHARLESWORTH J |
Date of judgment: | 19 November 2026 |
Catchwords: | CONTRACTS – leases for the occupation of spaces at Darwin International Airport and Alice Springs Airport governed by the Business Tenancies (Fair Dealings) Act 2003 (NT) – provisions of leases providing for the review of rent following the first contract year – rent review provisions non-compliant with both s 28(2) and s 28(3) of the Business Tenancies (Fair Dealings) Act 2003 (NT) – provisions operating to limit the amount by which rent may be reduced – whether a provision that is void under s 28(3) may be considered under s 28(2) and subject to the remedy provided for in s 28(7) – meaning of the word “void” in s 28(3) – application for declaratory relief granted in part |
Legislation: | Acts Interpretation Act 1901 (Cth) s 15AA Business Tenancies (Fair Dealings) Act 2003 (NT) ss 3, 9, 12, 28, 32 Retail Leases Act 2003 (Vic) s 35 Retail Shop Leases Act 1994 (Qld) ss 27, 36 |
Cases cited: | Aldi Foods Pty Ltd v Northcote Shopping Centre Pty Ltd [2024] VSC 799 Gouger Street Pty Ltd v Diakou Nominees Pty Ltd [2024] SASCA 17 Project Blue Sky Inc v Australian Broadcasting Authority (1998) 194 CLR 355 Singh v Minister for Immigration, Citizenship, Migrant Services and Multicultural Affairs (2023) 299 FCR 464 |
Division: | General Division |
Registry: | Northern Territory |
National Practice Area: | Commercial and Corporations |
Sub-area: | Commercial Contracts, Banking, Finance and Insurance |
Number of paragraphs: | 65 |
Date of last submissions: | Applicant: 27 April 2026 Respondent: 17 April 2026 |
Date of hearing: | 7 April 2026 |
Counsel for the Applicant: | A Wyvill SC with J Wang |
Solicitor for the Applicant: | Maddocks |
Counsel for the Respondents: | H Baddeley SC with T Moses |
Solicitor for the Respondents: | HWL Ebsworth Lawyers |
ORDERS
NTD 20 of 2025 | ||
| ||
BETWEEN: | KINGMILL PTY LTD (ABN 58 003 966 649) TRADING AS SIXT AUSTRALIA Applicant | |
AND: | DARWIN INTERNATIONAL AIRPORT PTY LTD (ABN 87 081 258 157) First Respondent ALICE SPRINGS AIRPORT PTY LTD (ABN 19 081 258 246) Second Respondent | |
order made by: | CHARLESWORTH J |
DATE OF ORDER: | 19 November 2026 |
THE COURT DECLARES THAT:
1. Clause 6.1(a) and Sch 2 of the Darwin Licence and the Alice Springs Licence do not comply with s 28(3) of the Business Tenancies (Fair Dealings) Act 2003 (NT) to the extent that they contain provision for the review of rent payable in the second to fifth contract years because they operated to limit the extent to which rent may be reduced upon the review.
2. By reason of the matters declared in paragraph 1, cl 6.1(a) and Sch 2 of the Darwin Licence and the Alice Springs Licence are void in the sense that they are unenforceable mechanisms for the calculation of rent for the second to fifth contract years.
3. Clause 6.1(a) and Sch 2 of the Darwin Licence and the Alice Springs Licence do not comply with s 28(2) of the Act to the extent that they contain provision for the review of rent payable in the second to fifth contract years because they do not provide for the calculation of rent upon the review by one of the prescribed methods.
4. The rent payable under the Darwin Licence and the Alice Springs Licence for the second to fifth contract years is the amount to be determined in each case in accordance with s 28(7)(b) of the Act.
THE COURT ORDERS THAT:
1. The parties have liberty to apply to vary the Declarations, strictly confined to variations necessary to reflect the reasons for judgment published today, such liberty to be exercised by way of written submission filed on or before 3 December 2026.
2. Any party seeking an order as to costs is to file and serve, on or before 10 December 2026, an affidavit specifying the order sought together with written submissions not exceeding three pages.
3. Any application for costs made in accordance with the order in paragraph 2 is to be determined on the papers.
4. In the event that no application is made in accordance with the order in paragraph 2, there be no orders as to costs.
Note: Entry of orders is dealt with in Rule 39.32 of the Federal Court Rules 2011.
REASONS FOR JUDGMENT
CHARLESWORTH J:
1 The applicant, Kingmill Pty Ltd, operates an international car rental business, trading as SIXT Australia. On 10 June 2021 it entered into an agreement with the first respondent, Darwin International Airport Pty Ltd (DIA) licensing it to conduct a car rental and delivery business from specified areas at Darwin International Airport (Darwin Licence). On the same day, Kingmill entered into an agreement with the second respondent, Alice Springs Airport Pty Ltd (ASA), licensing it to conduct a car rental and delivery business from specified areas at Alice Springs Airport (Alice Springs Licence). Each Licence is a retail shop lease governed by the Business Tenancies (Fair Dealings) Act 2003 (NT). Each operated for a 5-year term, the first defined “contract year” commencing on 1 March 2020.
2 Kingmill alleges that it has overpaid rent under the Licences in the 2022-2023, 2023-2024 and 2024-2025 contract years. On its primary case it seeks declarations to the effect that a provision in each Licence for the calculation of rent is void to a specified extent because of the operation of s 28(3) of the Act, together with judgment in restitution for the repayment of $1,480,937.94 and $715,087.18 respectively: Further Amended Originating Application (OA), [1], [2], [6] and [7].
3 On an alternative case, Kingmill seeks declarations to the effect that each Licence does not comply with s 28(2) of the Act, together with a declaration that it is entitled to have rent for the disputed contract years determined as market rent under s 28(7)(b) of the Act: OA, [3] and [8].
4 The respondents do not dispute the alternate case.
5 For the reasons that follow, Kingmill’s primary case is not established. Relief will be granted in accordance with the admitted claims on the alternate case.
Terms of the Darwin Licence
6 The Darwin Licence and the Alice Springs Licence are in relevantly identical terms. It is convenient to resolve the disputed issues by reference to the terms of the Darwin Licence, as amended by a Deed of Variation made on 6 August 2021, with some occasional references to the factual operation of the Alice Springs Licence.
7 Clause 6.1(a) of the Darwin Licence required Kingmill to pay rent (referred to as a Licence Fee) in accordance with Schedule 2. As no other Schedule will be mentioned in these reasons, I will now refer to the content of Schedule 2 only by its paragraph numbers.
8 Paragraph 1 imposes an obligation to pay the Licence Fee in the amount and manner specified in the following paragraphs.
9 Paragraph 2 is as follows:
2. Calculation of Licence Fee
a. For each Contract Year, the Licence Fee is the greater of the Annual Percentage Amount and the Minimum Guaranteed Licence Fee.
b. The Annual Percentage Amount = Annual Gross Revenue x 19%
In this formula:
Annual Gross Revenue is the Gross Revenue for the Contract Year
c. The Minimum Guaranteed Licence Fee = Guaranteed Income Per Arriving Passenger (GIPAP) x Annual Actual Arriving Passengers
In this formula:
GIPAP is:
1. in relation to the Contract Year commencing on the Commencement Date: $0.30 per Actual Arriving Passenger
2. in relation to each subsequent Contract Year (Applicable Contract Year): (LF / AAP x 80%)
where
LF is the Licence Fee for the Contract Year prior to the Applicable Contract Year
AAP is the number of Actual Arriving Passengers in the Contract Year prior to the Applicable Contract Year (provided that if the number of Actual Arriving Passengers in the Contract Year prior to the Applicable Contract Year is zero, it is deemed to be one for the purposes of this formula)
Annual Actual Arriving Passengers is the number of passengers (including international and domestic passengers, but excluding transit passengers and passengers on military charters) that arrived at the Airport during the Contract Year.
d. Where clause 15.4 applies, the Licence Fee for the Contract Year is calculated in accordance with clause 15.4.
(emphasis in original)
10 Annual Gross Revenue is defined. In submissions the parties used the phrase interchangeably with “turnover” and I may do the same.
11 As can be seen, paragraph 2(c)(1) makes a separate provision for the calculation of rent in the first contract year, that formula not incorporating any reference to a Licence Fee paid in a prior year.
12 The manner of payment is specified in paragraphs 4 to 6 to the following effect. The Licence Fee was to be paid in monthly payments on account, then adjusted at the end of each contract year. Paragraph 4(c) required that Kingmill calculate and submit a statement showing its turnover and a Monthly Percentage Amount (being 19% of the monthly turnover) for the past month. Each month, DIA was required to provide Kingmill with a statement showing Actual Arriving Passengers and the Minimum Guaranteed Monthly Licence Fee for the Relevant Month: paragraph 4(d). Assuming the production of that information, the amount payable for the relevant month was the higher of the Monthly Percentage Amount and the Minimum Guaranteed Monthly Licence Fee: paragraph 4(f). There was then provision for an adjustment payment to be made following the end of the contract year depending on whether the Licence Fee payable was greater or lesser than the amount paid for in that year: paragraph 5. It is by that mechanism that rent in each contract year was paid in monthly amounts, notwithstanding that the annual figures necessary to calculate the actual rent payable would not be available until the completion of that contract year.
13 It is common ground that in the disputed contract years, paragraph 2 operated as a rent review clause. In accordance with the authorities, it may be characterised as a “mixed”, “multiple” or “combined” review formula: Aldi Foods Pty Ltd v Northcote Shopping Centre Pty Ltd [2024] VSC 799 at [26], [40] – [43], [52] (Croft J); Gouger Street Pty Ltd v Diakou Nominees Pty Ltd [2024] SASCA 17 at [71] (Livesey P, Doyle JA and Blue AJA). That is because it was comprised of two formulae (the Annual Percentage Amount (APA) and the Minimum Guaranteed Licence Fee (MGLF)) with different inputs yielding different monetary amounts and a mechanism for choosing which of the amounts is the amount payable. The phrase “the greater of” provides the mechanism for making that choice: the rent payable is the greater of the sums yielded by the APA on the one hand and the MGLF on the other.
14 Each of the APA and the MGLF is wholly or partially affected by market conditions, being Kingmill’s turnover (APA) and the number of passengers arriving at the Darwin International Airport in a relevant year (MGLF).
15 As can be seen, the Guaranteed Income Per Arriving Passenger (GIPAP) amount is to be inserted into the formula for the calculation of the MGLF.
16 When the GIPAP is inserted into the MGLF, the MGLF formula is as follows:
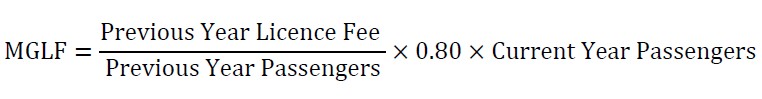
17 In its practical operation, the MGLF formula was capable of yielding amounts that could increase or decrease year by year according to the inputs. As Kingmill submitted:
(1) if the number of passengers arriving at Darwin International Airport is the same from one year to the next, then the MGLF will be 80% of the previous year’s Licence Fee;
(2) if the number of passengers arriving at Darwin International Airport increases by 50% from one contract year to the next, then the MGLF will be 120% of the previous year’s Licence Fee; and
(3) if the number of passengers arriving at Darwin International Airport decreases by 50% from one contract year to the next, then the MGLF will be 40% of the previous year’s Licence Fee.
18 As discussed below, whether an amount that was 80%, 120% or 40% of the previous year’s Licence Fee is “greater than” the APA in a particular year would depend on the outcome of the APA formula, that is, according to Kingmill’s turnover in the relevant year.
The rent paid
19 In the first two contract years under each Licence (2020-21 and 2021-22), Kingmill’s former franchisee paid rent to DIA and ASA calculated by reference to the APA, that is, 19% of turnover. In oral submissions, Kingmill asserted that rent in the first year was the sum yielded by the APA because that is what the parties “agreed”. The assertion was said to be evidenced by the fact that each Licence was signed some 15 months after the commencement of the first contract year.
20 To the extent that the submission meant that paragraph 2(a) did not operate in accordance with its terms in the first contract year, the submission is not supported by evidence. The terms of each Licence stated that in each of the first and second contract years the sum yielded by the APA formula was greater than the sum yielded by the MGLF. The amount paid in the first year is explained by the provisions operating in accordance with their terms, specifically by way of monthly statement exchanges and annual adjustments referred to at [12] above.
21 It is common ground that passenger numbers increased very sharply following the COVID-19 pandemic, resulting in an increase in the sum yielded by the MGLF formula in subsequent contract years well exceeding the APA. As a consequence, the rent payable exceeded 19% of Kingmill’s turnover, and drastically so. In those years, the respective rent under the Darwin Licence amounted to 51.82%, 51.88% and 42.02% of Kingmill’s revenue. In the fourth and fifth contract years the respective rent under the Alice Springs Licence amounted to 76.43% and 108.81% of Kingmill’s revenue. No submissions were made about the legal consequence of the rent exceeding revenue. Rather, the pleaded case and submissions focussed upon the statutory consequence of non-compliance with s 28 of the Act, to which I now turn.
The Act
22 The objects of the Act are to enhance (among other things) the certainty and fairness of retail shop leasing arrangements between landlords and tenants: Act, s 3.
23 Section 28 provides:
28 Rent reviews generally
(1) If a retail shop lease provides for a review of the rent payable under the lease or under a renewal of the lease, the lease is to state:
(a) when the reviews are to take place; and
(b) the basis or formula on which the reviews are to be made.
(2) The basis or formula on which a rent review is to be made is to be one of the following:
(a) a fixed percentage;
(b) an independently published index of prices or wages;
(c) a fixed annual amount;
(d) the current market rent of the retail shop lease;
(e) a basis or formula prescribed by the Regulations.
(3) A provision of a retail shop lease is void to the extent that it precludes or prevents a reduction of rent or limits the extent to which rent may be reduced.
(4) Subsection (3) does not apply to a provision that uses:
(a) a basis or formula mentioned in subsection (2)(a), (b) or (c); or
(b) a basis or formula prescribed under subsection (2)(e) that is also prescribed as a basis or formula to which subsection (3) does not apply.
(5) A rent review is to be conducted as early as practicable within the time provided by the lease, and if the landlord has not initiated the review within 90 days after the end of that time the tenant may initiate the review.
(6) A rent review provision in a retail shop lease is void if the lease does not specify how the review is to be made.
(7) If a provision in a retail shop lease that provides for a review of the rent payable under the lease does not comply with subsection (2), the rent is to be:
(a) as agreed between the landlord and tenant; or
(b) if there is no agreement within 30 days after the landlord gives the tenant, or the tenant gives the landlord, a written notice specifying an amount of rent for the purposes of the review – the amount determined as the current market rent of the retail premises by a specialist retail valuer appointed by the Commissioner.
(8) The landlord and the tenant are to pay the costs of the valuation under subsection (7) in equal shares.
24 The Act operates despite the provisions of a retail shop lease, and a provision of a retail shop lease is void to the extent that it is inconsistent with a provision of the Act: Act, s 9.
25 Section 32 provides that where rent (or any component of rent) is calculated by reference to turnover, the calculation must not include amounts then specified in s 32(1)(a) through to (l).
26 In the Second Reading Speech for the Bill that became the Act, the Attorney-General described a “ratchet clause” as a clause in a lease that provided for rent to increase in line with upward market trends but not to decrease in the event of economic decline. The Attorney-General stated that the prohibition on ratchet clauses had been “retained” in the Bill on the basis that it was unfair to link rent review to the market but only where the market would produce a higher rent. The Attorney-General also noted that rent increases could nonetheless be obtained by lessors by, for example, linking rent to the Consumer Price Index. The Attorney-General said that ratchet clauses “appear to be prohibited in every other Australian jurisdiction”: Business Tenancies (Fair Dealings) Bill 2003 (NT), Northern Territory, Parliamentary Debates, Legislative Assembly, 21 August 2003 at 4939.
27 Section 28(2) and (3) of the Act are in similar terms to s 35(2) and (3) of the Retail Leases Act 2003 (Vic). In Aldi, Croft J explained that the purpose of such provisions was to prohibit “mixed” formulae being used in rent review provisions (at [52]). His Honour continued:
However, the structure of s 35 now separates the permissible rent review formula provisions, which are contained in s 35(2), from the provisions with respect to rent review outcomes, now addressed in s 35(3). In my view, this is not merely a drafting change but, rather, reflects in this legislation “a new scheme” with respect to the permissible rent review regime. It is also an approach, as the review of legislative approaches the earlier acts makes clear in the preceding discussion in these reasons, indicating that the legislature was concerned, and has maintained that concern, to prevent rent review formulae being combined for the purpose of providing for or enabling landlords to opt for ever increasing rents as a result of review processes. Section 35(3) is consistent with the rent review provisions of the legislation since the [Retail Tenancies Act 1986 (Vic)] in that it renders void a provision which enables prevention of the reduction of rent, or reduction of rent to a limited extent, on a rent review. This addresses clearly the “evil” to which the legislature has been directing itself since the [Retail Tenancies Act 1986 (Vic)]. However, consistently with the legislative approaches in that act and subsequently, there is no prohibition in s 35(2) on maximum caps on rent increases. Having regard to this legislative history and the express words of s 35 this cannot, in my view, be viewed as anything but significant. It cannot be viewed as a mere legislative “accident” or “omission”.
(citations omitted)
Admitted non-compliance with section 28(2)
28 The respondents each admit that the “combined” review formula in paragraph 2 does not comply with s 28(2) because the formula is not “one of the” things mentioned in subs (2)(a) to (e) but rather a formula comprising a combination of things with a mechanism for choosing between them. Were it necessary to decide the point I would have no hesitation concluding that paragraph 2 does not comply with s 28(2) of the Act for that reason.
29 The consequences of non-compliance with s 28(2) are prescribed in s 28(7). If the rent is not agreed within a prescribed time, then the rent will be the amount determined as the current market rent by a specialist retail valuer appointed by the Commissioner of Business Tenancies (a person identified or appointed under s 12).
Disputed operation of section 28(3)
30 Kingmill’s primary case is that there is no occasion to apply s 28(2) because s 28(3) operates in such a way that the rent in each contract year is to be determined by the APA (a permissible calculation for turnover rent expressly contemplated by s 32 of the Act) with no surviving mechanism for rent review.
31 The starting point on the primary case is that s 28(3) of the Act renders void a rent review provision to the extent that (and only to the extent that) it has the proscribed effect.
32 Section 28(3) is focussed not so much on the characterisation of a formula (as in s 28(2)) but on the outcome of the operation of a contractual provision. The proscribed outcome is one that precludes or prevents a reduction of rent or that (more saliently for present purposes) prevents or limits the extent to which rent may be reduced.
33 In their pleading, the respondents denied non-compliance with s 28(3). However, their written and oral submissions acknowledged non-compliance. The parties remain in dispute as to the manner in which paragraph 2 brings about the proscribed effect and hence dispute the remedial operation of s 28(3).
34 Kingmill submitted that in order to identify that part of the impugned provision that is void under s 28(3) of the Act, it is necessary to identify that part of the provision that supplies the “rent” and the part that supplies the “ratchet”. It was submitted that the ratchet must then be severed in accordance with s 28(3), leaving only the rent to survive. It invited the Court to find that the rent was the APA and the ratchet was the MGLF.
35 Kingmill submitted that the rent under each Licence (the APA) was, in every contract year, a form of turnover rent the legitimacy of which was recognised by s 32 of the Act and was not to be characterised as incorporating a rent review. Accordingly, it was submitted, the statutory severance required by s 28(3) of the Act meant that there remained no rent review mechanism at all. Hence, it did not matter that turnover rent was not a formula for the determination of rent mentioned in s 28(2) of the Act which was confined in its operation to provisions relating to rent reviews. On that approach, s 28(3) of the Act would require that paragraph 2 be read as follows (the markup is supplied by Kingmill, and is drawn from the Alice Springs Licence but the same contention is raised with respect to the Darwin Licence):
2. Calculation of Licence Fee
a. For each Contract Year, the Licence Fee is the greater of the Annual Percentage Amount and the Minimum Guaranteed Licence Fee.
b. The Annual Percentage Amount = Annual Gross Revenue x 19%
In this formula:
Annual Gross Revenue is the Gross Revenue for the Contract Year
c. The Minimum Guaranteed Licence Fee = Guaranteed Income Per Arriving Passenger (GIPAP) x Annual Actual Arriving Passengers
In this formula:
GIPAP is:
1. In relation to the Contract Year commencing on the Commencement Date: $0.84 per Actual Arriving Passenger
2. In relation to each subsequent Contract Year (Applicable Contract Year): (LF / AAP x 80%)
where
LF is the Licence Fee for the Contract Year prior to the Applicable Contract Year
AAP is the number of Actual Arriving Passengers in the Contract Year prior to the Applicable Contract Year (provided that if the number of Actual Arriving Passengers in the Contract Year prior to the Applicable Contract Year is zero, it is deemed to be one for the purposes of this formula)
Annual Actual Arriving Passengers is the number of passengers (including international and domestic passengers, but excluding transit passengers and passengers on military charters) that arrived at the Airport during the Contract Year.
d. Where clause 15.4 applies, the Licence Fee for the Contract Year is calculated in accordance with clause 15.4.
36 The markup supplied by Kingmill also included modifications to paragraph 4 (relating to the manner of payment), redacting references to the MGLF, GIPAP and “greater than” mechanisms, but leaving intact references to the APA and the requirement for monthly returns by reference to the APA alone.
37 Kingmill submitted that there were three reasons to characterise the outcome of the APA formula as rent and the outcome of the MGLF formula as the ratchet. First, it submitted that the rent in the first contract year was agreed to be the APA amount and that the amounts payable in the disputed contract years were outcomes well in excess of 19% of turnover (evidencing that the MGLF conferred on the landlord “enhanced entitlements”). Secondly, the GIPAP was comprised of a formula with a built-in rent review mechanism after the first contract year because it had, as an input component, the rent paid in the previous contract year. Thirdly, it was submitted that the APA should be identified as the rent because it was (standing alone) a permissible form of rent contemplated by s 32 of the Act whereas the MGLF formula (standing alone) would not comply with s 28(2).
38 It was submitted that once the “ratchet” was identified as void and severed from the Darwin Licence, the surviving part of paragraph 2 ought not be characterised as a rent review provision at all, with the consequence that there was no occasion to apply s 28(2) (and hence s 28(7)). That approach, it was submitted, would best promote the statutory objective of certainty and fairness. Kingmill submitted that certainty and fairness would not be achieved by the parties being required to engage in the “litigious” process under s 28(7) in the absence of agreement as to what the rent should be.
39 Kingmill submitted that the monetary relief on acceptance of the primary case should be calculated as follows:
AS AGAINST DIA | |||||
Contract Year | Corrected Gross Revenue (ex GST) | Licence Fee at 19% of Revenue (ex GST) | Licence Fee Actually Paid (ex GST) | LF Paid as % of Revenue | Amount Overpaid (ex GST) |
Year 3 Mar 2022 – Feb 2023 | 1,932,975.44 | 367,265.33 | 1,001,624.03 | 51.82% | 634,358.70 |
Year 4 Mar 2023 – Feb 2024 | 1,510,958.89 | 287,082.19 | 783,834.56 | 51.88% | 496,752.37 |
Year 5 Mar 2024 – Feb 2025 | 1,519,393.02 | 288,684.67 | 638,511.52 | 42.02% | 349,826.85 |
TOTAL | 4,963,327.35 | 943,032.19 | 2,423,970.11 | 1,480,937.92 | |
AS AGAINST ASA | |||||
Contract Year | Corrected Gross Revenue (ex GST) | Licence Fee at 19% of Revenue (ex GST) | Licence Fee Actually Paid (ex GST) | LF Paid as % of Revenue | Amount Overpaid (ex GST) |
Year 3 Mar 2022 – Feb 2023 | 0.00 | 0.00 | 326,000.33 | N/A | 326,000.33 |
Year 4 Mar 2023 – Feb 2024 | 348,263.65 | 66,170.09 | 266,184.03 | 76.43% | 200,013.94 |
Year 5 Mar 2024 – Feb 2025 | 210,525.41 | 39,999.83 | 229,072.74 | 108.81% | 189,072.91 |
TOTAL | 558,789.06 | 106,169.92 | 821,257.10 | 715,087.18 | |
Consideration
40 The controversy concerning the operation of s 28(3) of the Act is to be resolved by applying the statutory provision in accordance with its terms to the impugned contractual provision, properly construed. The Court is not assisted in that task by seeking out within the contractual provision an amount that constitutes the “rent” and an amount that constitutes the “ratchet”. The label “ratchet” is unnecessary and apt to distract because the word forms no part of the statutory test. The Court’s task is to identify whether paragraph 2 has the effect prohibited by s 28(3) and, if so, how.
41 Kingmill’s submission that a “rent review mechanism” is to be found in and only in the MGLF should be rejected as it ignores the existence and terms of the rent review mechanism provided for by paragraph 2(a): for each contract year, the Licence Fee is the greater of the APA and the MGLF. That is the subclause that operates to change the rent from year to year. It is by virtue of that change that paragraph 2 “provides for a review of the rent” within the meaning of s 28(1) of the Act so exposing it to the Court’s scrutiny against the requirement in s 28(3).
42 Kingmill contended that the MGLF formula (as its full name suggests) supplied the minimum amount that would be payable in each year irrespective of Kingmill’s turnover. The name does indeed suggest an operation of that kind. However, it is necessary to focus on the substantive operation of the contractual provision and not the name parties chose for it.
43 Six further observations may be made about the substantive operation of paragraph 2.
44 First, the sum yielded by the APA may vary in each contract year, whether upward or downward, according to Kingmill’s revenue.
45 Secondly, the sum yielded by the MGLF may also vary in each contract year, whether upward or downward, according to footfall at the relevant airport.
46 Thirdly, the MGLF will not in all years yield a sum greater than that yielded by the APA. So much is demonstrated by the first and second contract years in which paragraph 2(a) operated to supply the APA amount as the rent, it being greater than the MGLF amount in those years.
47 Fourthly, paragraph 2 does not operate to increase the rent from one contract year to the next precluding any decrease. So much is demonstrated by the successive decreases in rent in the third, fourth and fifth contract years under both Licences.
48 Fifthly, neither the APA nor the MGLF, considered in isolation, has the effect proscribed in s 28(3). Considered separately, neither precludes or prevents a reduction of rent or limits the extent to which rent may be reduced. They are each affected by negative and positive market forces. Considered in isolation, neither purports to fix a minimum floor or maximum ceiling.
49 Sixthly, paragraph 2 nonetheless offends s 28(3) of the Act because paragraph 2(a) selects the higher of the two sums yielded by the APA and the MGLF, so preventing or precluding the rent from being the lower sum and otherwise limiting the extent to which the rent may be reduced. The provision operates in that way because where the impact of negative market forces on Kingmill’s turnover is greater than the impact of negative market forces on the airport footfall, the rent will reflect only the impact on the footfall. Importantly, the reverse may also occur. Where the negative market forces impacting on the footfall are greater than the negative market forces impacting on the turnover, the rent will reflect only the impact on the turnover. In either case, the question of whether the rent will decrease in comparison to the prior year will depend on the outcome of the calculation in the prior year. If there is a reduction, the reduction is one that is limited by the mechanism in paragraph 2(a). It is therefore the operation of paragraph 2(a) that offends s 28(3) of the Act, not any discrete part of the mixed formulae. There is no basis for identifying the MGLF (or only MGLF) as the culprit in the lineup.
50 It remains to consider the interaction between s 28(2), s 28(3) and s 28(7) of the Act.
51 On its primary case, Kingmill submitted that the Court was to approach the issues in dispute first by ascertaining the extent to which paragraph 2 of Sch 2 in each Licence was void under s 28(3), with the result that the offending portion must then be severed leaving some of it to survive. Kingmill submitted that the market rent review under s 28(7) of the Act could only then apply if the surviving portion (if any) could be characterised as a review clause that does not employ one of the permitted review methods listed in s 28(2).
52 The respondents submitted that s 28(2) and (7) apply in accordance with their terms and that their operation is not affected by the additional remedial mechanism in s 28(3).
53 The controversy distils to a question about the meaning of the word “void” in s 28(3) of the Act. Both parties drew on the decided cases to support their opposing construction arguments. The decided cases do not directly address the question of construction that arises in this case and some of them arise in different statutory and contractual contexts. It is unnecessary to discuss them at any length because they do not supply the answer to the dispute before me. The controversy can be resolved by applying well-established principles of statutory interpretation, construing the provisions in accordance with their text, context and purpose: Project Blue Sky Inc v Australian Broadcasting Authority (1998) 194 CLR 355 at [69] – [71] (McHugh, Gummow, Kirby and Hayne JJ); Acts Interpretation Act 1901 (Cth), s 15AA.
54 Each statutory provision addresses a different mischief, and each has different remedial consequences. The purpose of s 28(3) is to render inoperative any review mechanism having the proscribed outcome and so address the mischief referred to by the Attorney-General in the Second Reading Speech discussed above. The purpose of s 28(2) is to limit the review mechanisms that may be agreed by the parties and, together with s 28(4), to carve out some lease provisions from the operation of s 28(3). Importantly, where a provision offends s 28(2) the remedial response is not to rewrite a lease in a way that would provide for no rent review at all. Nor does it permit the tenant in a “mixed” formula case to select which formula is to apply. Express words would be required to support such a meaning. See, for example, s 27(7)(c), s 27(11) and s 36(1)(d) or (e) of the Retail Shop Leases Act 1994 (Qld) which provide in combination formula cases for rent to be worked out on one of the bases elected by the tenant. Section 28(7) gives effect to the parties’ intent that there be a review of the rent each contract year, and supplies the manner and method by which the review is to occur in substitution for the non-compliant method.
55 On its face, s 28 of the Act contemplates that there may be a provision in a lease that does not comply with the requirement in subs (2) and the requirement in subs (3). In the absence of an express provision to the contrary, a construction that allows both provisions to operate on an impugned contractual provision should be preferred given their discrete purposes. That is especially so in the absence of an express command that one statutory provision be given primacy over the other.
56 The statutory provisions may also work in conjunction with a contractual provision relating to reading down and severance, such as this provision in cl 36 of each Licence:
36. SEVERABILITY AND READING DOWN
If a provision of this Licence is reasonably capable of an interpretation which would make that provision valid and enforceable and an alternative interpretation that would make it unenforceable, illegal, invalid or void then that provision will be interpreted or construed, so far as is possible, to be limited and read down or severed to the extent necessary to make it or this Licence valid and enforceable.
57 In the present case however, cl 36 cannot save any part of paragraph 2 of Sch 2 insofar as it provided a mechanism for the calculation of rent in the second to fifth contract years.
58 Section 28(3) renders a provision of a lease void, but only to the extent that it has the proscribed effect. Confining s 28(3) to its purpose, the word “void” should be understood to deny the impugned lease provision the proscribed legal effect it would otherwise have. To fulfil the statutory purpose, it is unnecessary to construe the word “void” in a way that would create a fiction that the bargain was never struck, or that would preclude a Court from finding that the bargain, as struck, is also non-compliant with the requirement in s 28(2). To give the word “void” that wider meaning would be to unnecessarily stretch s 28(3) beyond its field of intended operation.
59 It has been held in administrative law contexts that a decision may be void for some purposes and yet still exist as a decision in fact for other purposes: see, for example, Singh v Minister for Immigration, Citizenship, Migrant Services and Multicultural Affairs (2023) 299 FCR 464 and the cases cited therein. Whilst that is a different legal context, the same principle of statutory construction may apply: the word “void” can eliminate the existence of a contractual right or obligation recorded in an agreement without eliminating the fact of the agreement for other statutory purposes.
60 Paragraph 2 is void only to the extent that it cannot operate to preclude or limit a reduction in rent. However, it does not follow that the Darwin Licence and the Alice Springs Licence do not each meet the description of a retail shop lease that “provides for a review of the rent payable under the lease or under a renewal of the lease” within the meaning of s 28(1) of the Act. A lease may have the features mentioned in s 28(1) even if the basis or formula on which reviews are to be made may also be void under s 28(3). The basis or formula contained in the lease may be assessed for compliance against s 28(2).
61 I do not accept that the remedial mechanism in s 28(7) is productive of uncertainty, nor do I accept that it is a “litigious” outcome that ought to be avoided. The assessment of rent according to an independent market valuation is an orthodox commercial mechanism for rent to be determined in cases where it cannot be agreed.
62 Nothing in the Act evinces an intention that the statutory mechanisms in s 28(7) be precluded from operating in cases where a rent review provision also falls foul of s 28(3).
63 Applied to each of the Darwin Licence and the Alice Springs Licence:
(1) each is a retail shop lease that provides for a review of the rent payable under the lease;
(2) each states when the reviews are to take place (each contract year) and the basis or formula on which the reviews are to be made (the formula in paragraph 2);
(3) the combined formula by which the reviews are to be made has the effect proscribed under s 28(3) and is therefore void in the sense that it is legally unenforceable between the parties;
(4) in addition, the combined formula is not “one of” the things listed in s 28(2); and
(5) there being no agreement between the landlord and tenant as to what the rent should be, the rent on each review is to be the amount determined as the current market rent on a valuation conducted under s 28(7)(b).
64 The originating application will be allowed to the extent of the alternate case, admitted in any event by the respondents.
65 The parties should be heard as to costs.
I certify that the preceding sixty-five (65) numbered paragraphs are a true copy of the Reasons for Judgment of the Honourable Justice Charlesworth. |
Associate:
Dated: 19 November 2026