Federal Court of Australia
Goshawk Mining Pty Ltd v Hellyer Metals Pty Ltd, in the matter of Hellyer Metals Pty Ltd (in liq) [2026] FCA 1676
File number(s): | TAD 19 of 2026 |
Judgment of: | MCELWAINE J |
Date of judgment: | 10 November 2026 |
Catchwords: | CORPORATIONS – standing – application under s 90-20 of the Insolvency Practice Schedule (Corporations) – meaning of “creditor of the company” in s 5-30 – whether a contingent creditor claiming unliquidated damages is a person with a financial interest in the external administration – distinction between standing to apply for winding up order and entitlement to lodge proof of debt – held plaintiffs have standing CORPORATIONS – insolvency – application under s 90-15 of the Insolvency Practice Schedule (Corporations) to remove and replace a liquidator on grounds of actual or apprehended bias – essentiality of independence – multiple matters of concern that might lead a fair-minded observer to apprehend that the liquidator might not bring an impartial mind to the administration – liquidator appointed by persons responsible for transfer of company’s assets for no valuable consideration – liquidator retained solicitor who introduced those persons – failure to engage with creditors’ offers to fund investigation – failure to exercise statutory powers to get in all relevant company records – failure to investigate with alacrity – misconception of matters relevant to the recovery of assets – opaque funding agreement leading to an obvious conflict between the creditors’ interests and the personal interests of the former bankrupt directors – held apprehended bias established – liquidator removed and replaced |
Legislation: | Bankruptcy Act 1966 (Cth), s 73 Corporations Act 2001 (Cth), ss 530A, 530B, 530C, 545, 553, 588FB, 588FF, 596A, 596B, Sch 2 (Insolvency Practice Schedule (Corporations)) ss 5-30, 90-15, 90-20 Insolvency Practice Rules (Corporations) 2016 (Cth), r 70-40 Supreme Court Rules 2000 (Tas), r 937B |
Cases cited: | Australian Securities and Investments Commission v Franklin [2014] FCAFC 85; (2014) 223 FCR 204 Brash Holdings Ltd v Katile Pty Ltd [1996] 1 VR 24 Ebner v Official Trustee in Bankruptcy [2000] HCA 63; (2000) 205 CLR 337 Gadsden v MacKinnon (Liquidator), in the matter of Allibi Pty Ltd (in liq) [2023] FCA 647 In the matter of ACN 151 726 224 Pty Ltd (in liq) [2016] NSWSC 1801 In the matter of Columbia Holdings Pty Ltd [2017] NSWSC 1859 Independent Cement and Lime Pty Ltd v Brick and Block Co Ltd (in liq) [2010] FCA 352; (2010) 267 ALR 613 Jahani, in the matter of Ralan Group Pty Ltd (in liq) [2022] FCA 107; (2022) 159 ACSR 222 Lucas, in the matter of Filestock Pty Ltd (in liq) [2017] FCA 1425 Monks v Pieman Resources Pty Ltd [2025] FCAFC 121 QYFM v Minister for Immigration, Citizenship and Multicultural Affairs [2023] HCA 15; (2023) 279 CLR 148 Re Allebart Pty Ltd [1971] 1 NSWLR 24 Re FW Projects Pty Ltd (in liq) [2019] NSWSC 892 Re Gemwood Projects Pty Ltd (in liq) [2025] VSC 819; (2025) 177 ACSR 269 Re Jay-O-Bees; Rosseau v Jay-O-Bees [2004] NSWSC 818; (2004) 50 ACSR 565 Re Treadtel International Pty Ltd (No 2) [2016] NSWSC 791 Starbelle Energy Pty Ltd v Louttit (Liquidator), in the matter of Coal Contractors Pty Ltd [2014] FCA 1172 Treadtel International Pty Ltd v Cocco [2016] NSWCA 360; (2016) 316 FLR 318 |
Division: | General Division |
Registry: | Tasmania |
National Practice Area: | Commercial and Corporations |
Sub-area: | Corporations and Corporate Insolvency |
Number of paragraphs: | 101 |
Date of hearing: | 26 – 27 October 2026 |
Counsel for the Plaintiffs: | Mr MJ Galvin KC and Mr D Palmer |
Solicitor for the Plaintiffs: | Groom Kennedy Lawyers & Advisors |
Counsel for the Defendants: | Mr R Notley |
Solicitor for the Defendants: | Rostron Carlyle Lawyers |
ORDERS
TAD 19 of 2026 | ||
IN THE MATTER OF HELLYER METALS PTY LTD (IN LIQUIDATION) (ACN 662 575 073) | ||
BETWEEN: | GOSHAWK MINING PTY LTD First Plaintiff SAXBY CAPITAL INVESTMENTS PTY LTD Second Plaintiff | |
AND: | HELLYER METALS PTY LTD First Defendant LIAM THOMAS BAILEY Second Defendant | |
order made by: | MCELWAINE J |
DATE OF ORDER: | 10 NOVEMBER 2026 |
THE COURT ORDERS THAT:
1. Liam Thomas Bailey is removed as liquidator of Hellyer Metals Pty Ltd (in liq).
2. Adam Lee Johnston of Apex Advisory Australia of Suite 12, 11 Morrison Street, Hobart is appointed as liquidator of Hellyer Metals Pty Ltd (in liq).
3. Liam Thomas Bailey must forthwith deliver all books and records of Hellyer Metals Pty Ltd (in liq) to Adam Lee Johnston.
4. The question of costs of the proceeding will be determined on the papers as follows:
(a) The plaintiffs must file written submissions not exceeding three pages by 4.00 pm on 19 November 2026;
(b) Liam Thomas Bailey must file written submissions not exceeding three pages by 4.00 pm on 26 November 2026.
Note: Entry of orders is dealt with in Rule 39.32 of the Federal Court Rules 2011.
REASONS FOR JUDGMENT
MCELWAINE J:
Synopsis
1 Goshawk Mining Pty Ltd and Saxby Capital Investments Pty Ltd (plaintiffs) apply to remove Liam Thomas Bailey as liquidator of Hellyer Metals Pty Ltd, which entered a creditors’ voluntary liquidation on 22 January 2026. Hellyer Metals is part of a group of six companies that owned and operated the Hellyer Gold Mine in northwest Tasmania.
2 On 14 October 2023, Goshawk Mining as vendor entered into a Sale Agreement with Hellyer Metals to sell the goodwill, plant and equipment and other business assets of an alluvial tin mine at Mount Cameron in Tasmania. The Sale Agreement was later varied. The purchase price was $25 million. The purchase price was payable by $15 million in cash and the issue of 10% of the shares in Hellyer Metals, which the parties assessed as having a value of $10 million. The Sale Agreement did not settle. Disputes arose and Goshawk Mining contended that Hellyer Metals repudiated the Sale Agreement, which it accepted, resulting in termination. Goshawk Mining, in December 2023, commenced a proceeding in the Supreme Court of Tasmania against Hellyer Metals and claimed damages of $36.4 million. Hellyer Metals defended the proceeding and counterclaimed (Goshawk Mining proceeding).
3 Separately, in October 2023, Hellyer Metals and Saxby Capital entered into an agreement to provide corporate advisory services to Hellyer Metals relating to a pre-initial public offering fundraising to raise up to $32 million for Hellyer Metals. Disputes arose concerning that agreement, and Saxby Capital commenced a proceeding in the Supreme Court claiming damages for breach of contract in the amount of $159,318.50.
4 The Supreme Court made an asset freezing order in the Goshawk Mining proceeding on 2 December 2025, in the amount of $36.4 million against Hellyer Metals, Hellyer Gold Mines Pty Ltd, Hellyer Metals Underground Pty Ltd, Celestial Pacific Group Pty Ltd, Ivy Resources Pty Ltd and Keen Pacific Ltd. The primary basis for the order was that on 5 November 2025, Hellyer Metals transferred its only assets, being shares in subsidiary companies, to Celestial Group. Goshawk Mining contends that Celestial Group did not give any consideration for the transfers. Goshawk Mining is concerned that the transfer of shares is a voidable transaction within the meaning of one or more of the provisions at Part 5.7B of the Corporations Act 2001 (Cth).
5 As finally resolved in submissions, the plaintiffs contend that they have lost confidence in Liam Bailey as liquidator of Hellyer Metals and he should be removed on the grounds of actual, or if not, apprehended bias.
6 Liam Bailey resists and submits that the plaintiffs lack standing and, in any event, no proper cause for removal has been shown.
7 For the following reasons, I am satisfied that the plaintiffs have standing, that the ground of apprehended bias is made out and that it is in the best interests of the creditors that Liam Bailey be removed as liquidator and replaced with Adam Lee Johnston.
Events of October and November 2025
8 Prior to 5 November 2025, the corporate structure of the Hellyer Group (with Hellyer Metals identified as “The Company”), was:
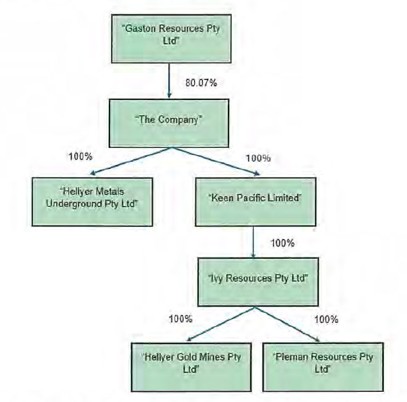
9 Hellyer Metals’ only assets were the shares held in each of the operating companies. That is, shares held directly in Hellyer Metals Underground and indirectly in Hellyer Gold, which companies operate the Hellyer Gold Mine. The plaintiffs are concerned that Liam Bailey has not taken any material steps to investigate the circumstances in which the shares in Hellyer Metals Underground and Hellyer Gold were transferred to Celestial Group in November 2025. The agreed chronology includes these events:
(1) 30 November 2020: Hellyer Metals’ subsidiary, Hellyer Gold purportedly enters into a senior secured facility agreement with ING Bank for US$55 million (Facility Agreement).
(2) 30 November 2020: Hellyer Gold purportedly enters into a priority, subordination and consent deed with ING Bank, RIVI Opportunity Fund LP, RCA NQ LLC and Audley Funding PLC (Priority Deed).
(3) 30 November 2020: Hellyer Gold purportedly enters into a general security deed with ING (General Security Deed).
(4) 30 November 2020: Hellyer Metals’ subsidiary, Ivy Resources (which then owned all shares in Hellyer Gold), purportedly enters into a specific security deed with ING Bank (Specific Security Deed).
(5) 22 December 2023: Goshawk Mining files a writ against Hellyer Metals for breach of contract and damages in the Goshawk Mining proceeding.
(6) 26 August 2025: Hellyer Metals files a notice of change of practitioner in the Goshawk Mining proceeding, replacing solicitors Ashurst Australia with RHR Legal.
(7) 20 October 2025: Hellyer Metals No. 1 Pty Ltd (Hellyer No.1) is incorporated as a subsidiary of Hellyer Metals.
(8) 22 October 2025: Hellyer No.1 purportedly enters a loan purchase and resignation agreement with ING, pursuant to which it purportedly acquires all rights, title and interests of ING Bank under the Facility Agreement, Priority Deed, General Security Deed and Specific Security Deed (LPRA).
(9) 30 October 2025: Goshawk Mining issues a subpoena to Graham Cox in the Goshawk Mining proceeding.
(10) 5 November 2025: Hellyer No.1, Hellyer Gold and Celestial Group purportedly enter a loan purchase and resignation agreement, pursuant to which Celestial Group purportedly acquires all rights, title and interests of Hellyer No.1 under the Facility Agreement, Priority Deed, General Security Deed and Specific Security Deed.
(11) 5 November 2025: Hellyer No.1 and Celestial Group as trustee for the Celestial Pacific Group Unit Trust purportedly enter into a binding offer deed (Binding Offer Deed), in connection with the rights acquired by Hellyer No.1 under the LPRA.
(12) 5 November 2025: All shares in Hellyer Gold are transferred from Ivy Resources to Celestial Group, and all shares in Hellyer Metals Underground are transferred from Hellyer Metals to Celestial Group (Transaction).
(13) 2 December 2025: Goshawk Mining obtains a freezing order in the Goshawk Mining proceeding against Hellyer Metals, Hellyer Gold, Hellyer Metals Underground, Ivy Resources, Keen Pacific, and Celestial Group (Freezing Order).
(14) 18 December 2025: The Freezing Order is ordered by the Supreme Court to continue until such further order in the Goshawk Mining proceeding.
10 Celestial Group was incorporated on 5 November 2025. Its original director and secretary, Louise Horrocks, is a solicitor and former General Counsel of Hellyer Metals. On 10 November 2025, Ms Horrocks was replaced as director by Graham Cox who, together with Karl Adolfsson, were the directors of Hellyer Metals until liquidation. Celestial Group’s sole shareholder is Alan Bates, who was an indirect shareholder in Hellyer Metals through his shareholding in Gaston Resources Pty Ltd. Gaston Resources was the major shareholder in Hellyer Metals, holding 556,785,316 ordinary shares, or approximately 95% of its issued shares. Mr Bates is also said to be a business associate of Graham Cox.
11 The significant matters of concern to the plaintiffs relate to the timing of the Transaction, the interrelationships between the actors and their related corporations and the apparent absence of any consideration paid by Celestial Group to Hellyer Metals. The last point focuses on the consideration clause of the Binding Offer Deed, whereby Celestial Group satisfied the obligation to pay the price of AUD $51,483,767 by assuming and discharging the liabilities, debts and obligations of Hellyer Metals. It is presently common ground that it appears not to have done so.
12 The interrelationship concerns were detailed in a letter from John Wilson of Groom Kennedy Lawyers, the plaintiffs’ solicitor, to Liam Bailey of 27 February 2026:
Individuals and entities related to the Hellyer Group
According to ASIC company searches:
(a) Gaston Resources holds approximately 95% of the shares in Hellyer Metals;
(b) ALB Management Pty Ltd (ALB Management) holds approximately 30% of the shares in Gaston Resources;
(c) Wise Old Elf holds approximately 27% of the shares in Gaston Resources;
(d) Alan Bates wholly owns ALB Management;
(e) Graham Cox wholly owns Wise Old Elf;
(f) On 5 November 2025, the following entities were incorporated in Australia:
i. Celestial Pacific Metals Pty Ltd (Celestial Metals);
ii. Celestial Pacific Investments Pty Ltd (Celestial Investments); and
iii. Celestial Pacific Group Pty Ltd (Celestial Group) –
who, along with Celestial Pacific Services Pty Ltd (Celestial Services), comprise the Celestial Entities.
(g) Alan Bates wholly owns Celestial Investments;
(h) Celestial Investments wholly owns Celestial Group;
(i) Celestial Group wholly owns both Celestial Metals and Celestial Services, on trust for one or more other parties or trusts;
(j) in addition to being the sole shareholder and sole director of Wise Old Elf, Graham Cox:
i. is a director of:
A. Hellyer Metals;
B. [Hellyer Gold];
C. Hellyer [Metals] Underground;
D. Celestial Metals;
E. Celestial Group; and
F. Celestial Services;
ii. was a director of:
A. Pieman Resources, until 22 October 2025;
B. Ivy Resources, until 22 October 2025; and
C. [Hellyer No.1], until 26 October 2025; and the sole director of Gaston Resources until 2 May 2024;
(k) Alan Bates is currently the sole director of Gaston Resources (succeeding Mr Cox), in addition to being the sole director and shareholder of both ALB Management and Celestial Investments;
(l) Karl Adolfsson is a director of:
i. Hellyer Metals;
ii. [Hellyer Gold];
iii. Pieman Resources;
iv. Ivy Resources;
v. Hellyer [Metals] Underground
vi. Celestial Metals; and
vii. Celestial Services;
(m) Louise Horrocks (who Goshawk [Mining] understands is Hellyer Metals’ general counsel) is a director and secretary of Celestial Group.
In summary, Goshawk [Mining] understands that both the Hellyer Group and the Celestial Entities are ultimately owned and/or controlled (either directly or indirectly) by Mr Cox, Mr Bates, Mr Adolfsson and Ms Horrocks.
The liquidation of Hellyer Metals
13 Liam Bailey was first consulted by Karl Adolfsson and Graham Cox in mid-January 2026. On 15 January 2026, Liam Bailey corresponded with each about the proposed voluntary winding up of Hellyer Metals. He provided the statutory documents required for the appointment process. Amongst other things, Karl Adolfsson and Graham Cox signed an undated resolution that the company was insolvent and unable to pay its debts.
14 Liam Bailey in his Statutory Report to Creditors dated 22 April 2026 pursuant to r 70-40 of the Insolvency Practice Rules (Corporations) 2016 (Cth), stated that Hellyer Metals was wound up voluntarily by its sole member on 22 January 2026. That statement cannot be reconciled with the list of 29 shareholders in the report, of which Gaston Resources was the majority shareholder. The minutes of the meeting of the shareholders of Hellyer Metals record that Alan Bates from Gaston Resources, Graham Cox from Wise Old Elf Advisory Pty Ltd and Karl Adolfsson from Pilumnus Capital Pty Ltd attended when the winding up resolution was passed. The combined shareholding of those companies was recorded as at least 95%.
15 The financial position of Hellyer Metals is summarised in the Statutory Report:
Notes | SoA ($) | ROCAP ($) | Estimated Realisable Value ($) | |
ASSETS | ||||
Cash at Bank | 6.1.1 | Nil | 3 | TBD |
Related Party Loan Accounts | 6.1.2 | Nil | 3,747,062 | TBD |
Contingent Asset | 6.1.3 | 100,000,000 | Nil | TBD |
Legal Proceedings | 6.1.4 | 55,000,000 | Nil | TBD |
Security for Costs | 6.1.5 | 322,000 | Nil | TBD |
Total assets | 155,322,000 | 3,747,065 | – | |
LIABILITIES | ||||
Secured Creditors | 6.2.1 | – | Nil | TBD |
Priority Creditors | 6.2.2 | 236 | Nil | 236 |
Unsecured Creditors | 6.2.3 | 1,433,225 | Nil | 7,625,726.34 |
Contingent Creditors | 6.2.4 | 36,100,000 | Nil | TBD |
Total liabilities | $37,533,461 | – | $7,625,963 | |
ESTIMATED DEFICIENCY | 117,788,539 | 3,747,065 | ($7,625,963) |
16 Something more should be noted about security for costs as disclosed in that summary. In the Goshawk Mining proceeding, on 17 April 2025 Goshawk Mining paid into court $578,000 as security for costs. Hellyer Metals defended the proceeding by defence and counterclaim. It subsequently provided security for costs of the counterclaim, in the amount of $322,000 which is recorded as an asset. Neither security has been released.
17 Prior to accepting appointment as liquidator, Gaston Resources provided a Deed of Guarantee and Indemnity to Liam Bailey for his remuneration in the amount of $50,000, inclusive of disbursements.
18 On 27 January 2026, John Wilson emailed Liam Bailey’s office, gave notice that he acted for Goshawk Mining and Saxby Capital and invited Liam Bailey to advise when he would have time to discuss issues relevant to the Supreme Court proceedings and the winding up. Liam Bailey responded later that day and invited John Wilson to nominate suitable days and times for an appointment. No meeting occurred before Liam Bailey issued his initial report to creditors on 6 February 2026. He issued an updated version on 8 February 2026. The initial report recorded that Hellyer Metals “was the ultimate holding company” for the Hellyer Group, then continued:
I understand that the company restructured its operations in November 2025 by transferring its assets to [Celestial Group]. Following the purported restructure the company lacked capacity to continue being represented in litigation to which it was a party.
To date, I have received limited information in respect of the financial position of the company or the other entities in the Hellyer Group. I have also received limited records pertaining to the purported restructure by which the assets of the company were sold.
My enquiries regarding the circumstances of the restructure are ongoing and I am awaiting further particulars from the Directors and [Hellyer Metals’] former legal advisors. I have made preliminary arrangements to interview the Directors and their advisors in the coming weeks. I have also had discussions with certain creditors about funding substantial investigations and potentially even public examinations should such be warranted on the conclusion of my preliminary enquiries.
19 On 27 February 2026, Marisa Gillam of Groom Kennedy Lawyers emailed proofs of debt from Goshawk Mining and Saxby Capital to Liam Bailey’s office respectively in the amounts of $36.4 million and $159,318.50. In separate correspondence from John Wilson to Liam Bailey, also dated 27 February 2026, the background to the disputes between Goshawk Mining, Saxby Capital and Hellyer Metals was set out in considerable detail. The factual basis for a belief that there had been conduct that may engage the provisions of Part 5.7B of the Corporations Act was also set out. The Transaction was the subject of particular focus, concluding with:
Goshawk [Mining] considers that:
(a) the Transaction was not conducted on an arm’s-length basis, and no bona fide consideration was provided in exchange for the shares;
(b) Hellyer Metals sought to alienate its assets (specifically, its shares in [Hellyer Gold] and Hellyer [Metals] Underground) by transferring them out of the Hellyer Group to Celestial Group;
(c) timing and structure of the Transaction give rise to a serious concern that its purpose and effect was to defeat creditor claims, including our clients claims; and
(d) the Transaction appears to constitute (without limitation) and uncommercial transaction pursuant to s 588FB of the Corporations Act (the Act) and creditor-defeating disposition pursuant to s 588FDB of the Act.
20 Under the heading “Next Steps”, the correspondence continued:
Our clients request that you, as liquidator for Hellyer Metals:
(a) provisionally admit Goshawk [Mining]’s claim against Hellyer Metals for voting purposes for the preliminary amount of $36.4 million and advise the process for adjudication;
(b) provisionally admit Saxby Capital’s claim against Hellyer Metals for voting purposes for the preliminary amount of $159,318.50 and advise the process for adjudication;
(c) advise what documentation you require in order to assess the quantum of Saxby Capital’s claim and whether you have obtained documents disclosing the gross proceeds of the Wise Old Elf Transaction or other transactions that may attract a break fee;
(d) urgently assess and, if appropriate, take steps to challenge and seek recovery in respect of the Transaction;
(e) keep our clients informed of all material developments regarding the recovery efforts in respect of the Transaction, including the proposed compromise of any claims;
(f) advise as to what activity has been undertaken by you to date to recover assets transferred as part of the Transaction;
(g) advise as to whether a report pursuant to section 533 of the Act has been lodged and if so, whether any misconduct has been identified;
(h) preserve all records related to Hellyer Metals, our clients’ claims and the Transaction; and
(i) actively manage limitation periods applicable to potential Part 5.7B proceedings.
Our clients also request that you advise as to:
(a) whether you presently consider the Transaction to be at an undervalue and creditordefeating, and whether there are any other transactions that you are aware of that are of a similar nature;
(b) whether you consider that recovery proceedings in respect of the Transaction are commercially viable;
(c) whether you intend to pursue such claims;
(d) whether you would consider assignment of causes of action;
(e) whether you hold all documents referred to in this letter and if not, which ones you require us to provide to you;
(f) whether you intend to seek return of the funds paid into Court for security for costs and, if so, on what basis; and
(g) whether any directors’ and officers’ insurance policies have been identified and whether notification has been made.
Our clients request you to please provide responses to the above points within 14 days of the date of this letter.
21 No response was provided within 14 days. On 17 March 2026, John Wilson corresponded with Carl Hagon of Rostron Carlyle Lawyers who previously acted for Graham Cox and Karl Adolfsson in the initial approach to Liam Bailey and later accepted instructions to act for Liam Bailey. He commenced by noting the failure of Liam Bailey to reply to his correspondence of 27 February 2026. At numbered paragraphs 5, 6 and 7 he said:
In particular, we would be grateful if you could advise:
a. whether your client has formed any preliminary view as to whether the Transaction may constitute an uncommercial transaction or creditor-defeating disposition;
b. whether your client presently intends to pursue recovery proceedings or other recovery action in relation to the Transaction;
c. what investigative steps your client has undertaken to date in relation to the Transaction;
d. whether your client is considering the use of the Court’s examination powers under section 596A or 596B of the Corporations Act in relation to the Transaction;
e. whether your client has obtained from the directors or former officers the books and records relating to the Transaction and the affairs of the Hellyer Group, including accounting records, bank statements, and documents relating to the Binding Offer Deed and Loan Purchase and Resignation Agreement;
f. how your client presently proposes to fund any recovery action;
g. the outcome of the proposed creditor resolutions;
h. whether your client is able to provide a schedule of creditors and proofs of debt received to date (including creditor names and claimed amounts).
Our clients remain willing to engage constructively with you regarding the conduct of the liquidation, including potential funding and assignment arrangements.
22 There was a cross-over of correspondence. Carl Hagon emailed Marisa Gillam and John Wilson on 17 March 2026 and relevantly stated:
Our client is grateful for the information and opinions set out in your letter of 27 February 2026.
We respond to the matters set out in your letter as follows:
1. We note that the resolution proposed pursuant to section 70-35 of Schedule 2 of the Corporations Act 2001 (Cth), proposed that Mr Bailey be entitled to destroy the books and records of the company within 6 months after the deregistration of [Hellyer Metals] (Original emphasis). We do not understand, therefore, how the matters raised in the paragraphs preceding paragraph 51 of your letter form a basis for your client to oppose the destruction of documents. In any event, your clients’ position is noted.
2. Similarly, we do not understand the basis for your clients’ opposition to the resolution regarding future fees. Our client is presently undertaking investigations regarding the various causes of actions available to him. As set out below, those investigations are not complete. As your clients would have discerned from a reading of the report to creditors, those investigations were at a nascent stage when the report was issued. Having not reached any view as to the existence (let alone commerciality) of any recovery from Celestial Group at that stage, an estimate of his proposed future fees which included the costs of those causes of action (if they exist) would have been premature and begged the question.
3. Our client notes, and agrees, with the matters raised in paragraph 53. That is the role he is statutorily obliged to perform. That is what he is doing.
4. As to paragraph 55:
(a) Our client is presently unable to admit (provisionally, whatever that means, or otherwise) Goshawk [Mining]’s claim in full. To do so would require our client to undertake an exercise that was, until our client's appointment, tasked to a judge of the Supreme Court Tasmania. Moreover, we understand that there is a substantial counterclaim filed by Hellyer Metals. For the purpose of the creditor’s meeting, our client would presently be prepared to admit your client's contingent claim for $1.00. This is the usual course. If your client seeks a formal adjudication of its claim our client will be required to obtain legal advice from a senior barrister. Our client is presently unfunded to obtain that advice. If your client wishes to fund our client to obtain that advice, our client will obtain three quotes for the provision of the advice and provide your client with a choice of barristers.
(b) We repeat the preceding paragraph in respect of Saxby [Capital]’s claim.
(c) Our client is in possession of all documents he deems necessary, but thanks your clients for the offer.
(d) We repeat our comments in respect of the causes of action available to our client set out at paragraph 2. In any event, as you note, freezing orders are in place so the assets are presently protected.
(e) Your clients, together with all creditors, will be made aware of the outcome of our client’s investigations when his statutory report is issued. Should there be any claims, and our client intends to compromise them, our client will comply with his duties pursuant to section 477 of the Corporations Act 2001 (Cth).
(f) Our client has obtained the full cooperation of the all (sic) related entities and has interviewed them and requested, and been provided with, all necessary documents.
(g) Such a step would be precipitous before our client’s investigations are complete.
(h) He is obliged to do so.
(i) Please advise what limitation periods you are referring to. It has been less than 2 months since our client’s appointment.
5. As to paragraph 56:
(a) We repeat our comments above.
(b) We repeat our comments above.
(c) We repeat our comments above.
(d) Our client would, at the appropriate time, consider assigning causes of action presuming:
(i) He is entitled to do so;
(ii) Creditor/Court approval was obtained, if necessary;
(iii) The value of any claims is properly understood;
(iv) Investigation of litigation funding options has been undertaken; and
(v) He ultimately formed the view that it was in the interest of creditors to assign any such claims;
(e) We repeat our comments above.
(f) Our client’s investigation of, inter alia, the counterclaim needs to be completed before he can properly form a view that the proceeding should be dismissed. Any opinion regarding the treatment of funds held in Court is posterior to that view being formed.
(g) Mr Bailey is advised that no D&O policies were taken out in respect of Hellyer Metals Pty Ltd.
23 On 27 March 2026, John Wilson sent further lengthy correspondence to Carl Hagon. Amongst other things he said:
Given the nature of the Transaction – including the timing of the transfers, the apparent absence of consideration and the involvement of related entities – our clients consider that this is a matter that warrant urgent and focused assessment. Does your client have a view as to how he proposes to fund the recovery of assets related to the Transaction, if pursued? Our clients are open to discussing potential options.
…
Given our clients positions in relation to the Transaction, our clients would be interested in exploring public examination in relation to the Transaction and would be open to discussing the funding of such action.
24 On 1 April 2026, Marisa Gillam emailed Carl Hagon, provided information that was then circulating in the media to the effect that the Hellyer Gold Mine was at risk of imminent closure and stressed the urgency of this matter in that if prompt action is not taken, creditors may be prejudiced. The media article stated that the Tasmanian Government had taken steps to revoke the mining lease.
25 On 22 April 2026, Liam Bailey issued the Statutory Report. In section 8, he summarised his investigations to date, focusing on the prospect of recovery proceedings pursuant to Part 5.7B of the Corporations Act. He noted that despite requests having been made to the directors he had not been provided with any formally prepared financial statements. He addressed the Transaction at paragraph 8.2. He set out the history relating to the ING Bank Secured Facility and noted that he had been advised that Hellyer No.1 had been incorporated “to acquire the position of ING as senior secured creditor” on the basis that ING received a payment of USD $10.5 million plus an assignment of receivables with an estimated value of between USD $4 million and $5 million. This placed Hellyer No.1 in the position of holding the first-ranking security over the assets of Hellyer Gold.
26 The Statutory Report further recorded that Liam Bailey had not been provided with sufficient material to assess whether the Transaction occurred at market value. Under his additional comments he stated:
Creditors ought to be aware of the following issues:
(i) It is apparent that there are issues with the transfer of Hellyer Gold and Hellyer [Metals] Underground to Celestial [Group] that require further investigation. It seems clear that Celestial [Group] did not actually assume any liabilities of Hellyer Gold or Hellyer [Metals] Underground that might constitute valid consideration of the transfers. Instead, it is noted that Celestial [Group] would need to recapitalise both companies to return them to solvency before they could trade. As such, it seems that the actual consideration paid by Celestial [Group] was in fact nil.
On one view, it could be said that at the date of transfer, the shares in Hellyer Gold and Hellyer [Metals] Underground had no value because the liabilities of each company exceeded the value of its assets. If this were correct, then the transactions would likely be uncommercial to pursue. However, an objective valuation of both the assets and the liabilities of those companies is required to confirm such a determination.
(ii) My role as Liquidator of [Hellyer Metals] does not authorise me to directly review the actions of Hellyer No.1 as it pertains to the enforcement of its security or the sale of that security to Celestial [Group]. If I formed the view that that transaction was conducted in a manner which breached the duties of Hellyer No.1 to [Hellyer Metals] as its sole shareholder, then I may seek to appoint a liquidator to Hellyer No.1 to investigate further.
For benefit to accrue to [Hellyer Metals], the value of the assets of Hellyer Gold would need to exceed the value of its liabilities, and those of Hellyer No.1, such that a distribution would have been made to [Hellyer Metals] from Hellyer No.1 if the transaction were conducted for value.
(ii) I am required to determine whether the shares in Hellyer [Metals] Underground had value. This would also require me to determine whether the value of the assets of Hellyer [Metals] Underground exceeded its liabilities by such a margin that a benefit would have flowed to [Hellyer Metals] as a distribution once all liabilities of Hellyer [Metals] Underground were discharged.
Should such a determination be made, then it is possible that the transfer of the shares in Hellyer [Metals] Underground may be voidable, or alternatively there may be a claim against the Directors of [Hellyer Metals] for a breach of duty.
(iii) It seems likely that any action commenced to void the transfer of the collective assets of the Hellyer Group to Celestial [Group] would likely destroy the value in those assets, noting the value seems to be in the continuing operations of the Hellyer Project operated by Hellyer Gold.
(iv) To advance any claims for the recovery of assets or against the Directors, I would require significant funding to conduct public examinations pursuant to section 596A of the Act, as well as funding for litigation thereafter should causes of action be identified and supported by evidence uncovered as part of that process.
Should any creditor wish to discuss the provision of such funding, then they should contact my office directly.
27 On 5 May 2026, the Tasmanian Minister for Business, Industry and Resources decided that he would not revoke the mining lease. On 6 May 2026, John Wilson sent further lengthy correspondence to Liam Bailey. He raised a number of concerns about the content of the Statutory Report, listing 15 detailed questions concerned with the Transaction. He expressed his clients’ disappointment that the Statutory Report failed to mention the interest that his clients had expressed in providing funding for undertaking investigations concerning the Transaction. Inter alia, he said:
In letters to you dated 17 March 2026 and 27 March 2026, we explicitly conveyed our clients’ willingness to engage constructively in funding arrangements or to take an assignment of claims if that would expedite recovery actions. Despite this, we have not been contacted on these offers and the [Statutory Report] instead issues a generic invitation for creditor funding.
Please provide a detailed plan of the investigations and recovery actions you propose (including the nature of any claims being considered under Part 5.7B of the Corporations Act (Cth)), and how you expect to resource them. Further, confirm when and how you will involve our clients – the largest external creditors – in discussions concerning funding or assignment of claims, as they have already offered.
28 Two questions were then posed: (1) whether Liam Bailey intended conducting public examinations, and if so when and of whom; and (2) if acceptable funding for public examinations is offered, whether Liam Bailey would be willing to conduct examinations without an advance commitment to fund subsequent litigation, and if not why. The final paragraph, once again, stressed the urgency of taking steps to investigate the Transaction.
29 On 7 May 2026, Carl Hagon emailed Marisa Gillam:
The Liquidator is currently considering how to resolve the uncertainty surrounding the status of Goshawk [Mining] and Saxby [Capital] as creditors of Hellyer Metals, noting that the status is disputed by [Hellyer Metals’] directors and shareholders. Until his position is resolved, the Liquidator reiterates that you are currently considered contingent creditors with an admitted value of $1.
A detailed response to your enquiries will be provided. In accordance with Insolvency Practice Rule 70-1, an extended timeframe is required to properly respond to the requests for information and the Liquidator intends to respond wholistically by no later than Friday 22 May 2026.
The Liquidator is cognisant of your client’s offer to fund further investigations and examinations and will, on resolution of the issues identified above, be in touch to discuss.
30 On 4 June 2026, Liam Bailey corresponded directly with John Wilson in answer to the letter of 6 May 2026. He first advised that the directors had requested that he adjudicate the proofs of debt of Goshawk Mining and Saxby Capital. Specifically, he said:
Adjudication of your Clients’ Claims as Creditors of [Hellyer Metals]
It will be no surprise that your status as creditors of [Hellyer Metals] is disputed by the Directors of [Hellyer Metals], who have formally requested that I adjudicate your Client’s proofs of debt (“POD”) lodged in the liquidation. Accordingly, for the reasons set out hereunder, I formally advise that I will;
a) mark the PODs as objected to and allow your Clients to vote in any meetings of creditors; and
b) admit the PODs for the nominal figure of $1 each in line with my just estimate of the value of the PODs.
My just estimate of your Clients’ PODs is based on the following;
(i) The claims in your Clients’ PODs are unliquidated or contingent claims for the purposes of regulation 75-85(4) of the Insolvency Practice Rules. This regulation precludes a creditor from voting unless a just estimate of the claims' values can be reached.
(ii) Corporations Regulation 5.6.26(2) states that if the chairperson of a meeting of the creditors of a company is in doubt whether a proof of debt or claim should be admitted or rejected, they must mark the proof as objected to and allow the creditor to vote.
(iii) I have doubts about the status of your Clients as creditors. That is because whether your Clients are creditors of [Hellyer Metals] or not turns, generally speaking, on whether the litigation into whether the conditions precedent of the agreements between your Clients and [Hellyer Metals] were satisfied either succeeds fully or fails utterly, and as to whether the counter claim by [Hellyer Metals] that your Clients engaged in misleading or deceptive conduct extinguishes some or all of your Clients claims.
(iv) Accordingly, I advise that based on the material currently available to me, I would mark the PODs as objected to and allow your Clients to vote at any meeting of [Hellyer Metals’] creditors.
(v) Having undertaken a review of the factual material furnished on me by your Clients, and in the total context of this matter and all material otherwise available to me, I am now required to advise as to my just estimate of the value of your Clients’ PODs.
(vi) It is currently impossible for me to determine any fixed amount to your Clients’ PODs. This is because their claims will either succeed fully or fail utterly and I am unable to form an opinion on this matter. Further, even if their claims succeed fully, then the counter claim by [Hellyer Metals] may extinguish some or all of the damages to which your Clients are entitled. Finally, there appear to be material issues by which the quantum of your PODs have been calculated and the admissibility of evidence relied upon in the application for freezing orders that cause to me to consider that their claims are more likely to fail than not and should not be considered as having a nil value.
(vii) However, in line with the judgement of Nixon J in In the matter of Mercon Group Pty Ltd (Subject to Deed of Company Arrangement) [2025] NSWSC 1601 at [98] to [103], and Austin J in Bovis Lend Lease Pty Ltd v Wily [2003] NSWSC 467; (2003) 45 ACSR 612 at [264] to [268], I will assess the just estimate of the value of your Clients’ PODs at the nominal value of $1.
(viii) Unless further information came to light by which I can assess the merits of the claims brought by your Clients that had not already been submitted to the Court, I would ultimately have little choice other than to reject your Clients’ PODs should I be called on to adjudicate them for dividend purposes.
31 Liam Bailey next addressed the “purported restructure and sale”. He said:
Purported Restructure and Sale
Following your summary of the content of my report to creditors dated 22 April 2026 (“the Report”), you make two observations. I advise as follows;
(i) I agree that the transfer of the shares in [Hellyer Metals Underground] may well be voidable and liable to be set aside under section 588FF of the Corporations Act 201 (sic) (“the Act”). It is not immediately apparent whether the shares in [Hellyer Metals Underground] had any value or whether such action would be commercial to pursue.
(ii) I consider that the transfer of the shares of [Hellyer Gold] to [Celestial Group] were part of a restructure of the entirety of the Hellyer Metals Group of Companies. It is not immediately apparent whether the shares in [Hellyer Gold] had any value, whether pursuing their recovery would be commercial to pursue or be of any benefit to [Hellyer Metals] and its creditors.
(iii) As noted in the [Statutory] Report, I am without finding to conduct further investigations into these matters and consider it unlikely that such investigations would proceed without conducting public examinations under section 596A of the Act. If your Clients would like to discuss funding such further investigations, I would be happy to schedule a virtual meeting to advance such discussions.
32 Next, he answered in detail each of the 25 requests for information. Two of his responses should be highlighted:
(m) As stated, my investigations into the restructuring transactions is limited by the availability of funding. If funded to do so, I consider the Transactions warrant further scrutiny by way of public examination.
(n) The recovery of the assets from Celestial [Group] would likely result in the termination of licenses and leases considered essential to the operations of the business of gold, especially in the absence of a fully funded plan to take over operations and to pay out the liabilities of gold immediate (sic) on resuming control of that company. It is otherwise evident that damages would be the more appropriate remedy to be sought from Celestial [Group] should any of the Transactions be voided.
33 He addressed funding in Part 6. He said:
I reiterate that at this time, the commerciality of pursuing further action against Celestial [Group], the Directors of the Company or the Directors of any subsidiary companies is far from certain, as are the merits of such claims. In relation to the transfer of the shares in [Hellyer Gold] by [Hellyer No.1] to Celestial [Group], it remains unclear whether I even have standing to pursue a claim to void such a transaction.
The only way to pursue such actions is through the conduct of public examinations following the receipt of legal advice on a number of the issues outlined in this letter. I have not sought detailed quotes to obtain the necessary legal advices and to conduct the necessary public examinations. In the ordinary course, a creditor would not offer funding until it had received a full outline of the circumstances of the company. Also, a liquidator would not undertake the considerable work required to set out the parameters of further investigations and legal work required unless such a fully informed creditor confirmed serious intentions to provide such funding.
If funded, I will proceed to obtain relevant legal advice on the issues outlined herein and seek quotes for the costs associated with conducting public examinations. I consider that the examination of any person that is or was a director of any of the companies within the Helleyer (sic) Group of Companies, as well as Louise Horrocks and the Directors of Celestial [Group] would all be examined as part of the public examination process.
Discussion in relation to the assignment of any causes of action are premature at this time as I have not adequately identified any causes of action in fact exist. I accept that taken at face value, there are numerous issues with the restructuring transactions that warrant further investigation and may give rise to choses in action to be pursued for the benefit of creditors. Subject to funding, these investigations will be undertaken and if commercial, action pursued for the benefit of creditors.
34 Liam Bailey, Carl Hagon, John Wilson, Marisa Gillam and Bradley Saxby met virtually on 5 June 2026. Bradley Saxby is a director of Goshawk Mining and Saxby Capital. He made two affidavits in this proceeding and was briefly cross-examined. There was no real challenge to his evidence. In his first affidavit, his evidence about this meeting was:
During the 5 June meeting, Mr Bailey stated words to the following effect:
(a) ‘I can request records from [Keen Pacific] until the cows come home but I'll get nothing.’
(b) ‘I have zero rights to access certain records in relation to Hellyer [Metals] Underground, [Hellyer Gold] or Celestial Group; that requires a public examination.’
(c) ‘I have nothing from Hellyer Metals No. 1 other than the deeds and limited balance sheets referred to in my report.’
(d) ‘What you are suggesting is a significant conspiracy to deny the creditors of Hellyer Metals the benefit of the transactions, that’s a much harder case to make out, the preliminary evidence I’ve looked at suggests the companies were encumbered by debt therefore there isn't a lost benefit.’
(e) ‘As a starting point for the value of shares, yes, a balance sheet equates to market value. A company that has more liabilities than asset value, it’s insolvent ... at face value, the position’s got to be that shares have no value, purely on the balance sheet.’
(f) ‘There are two options: 1) fund me to get a quote from a lawyer of your choice, or I ask a lawyer of my choice for a quote on the basis that they’re the one who is going to do the work, it’ll take 3-4 days’ worth of work to come to grips with all of this.’
(g) ‘I have no funding. This has reached the point now, I’ve spoken to litigation funders, they’re not interested. Unless a creditor wants to fund this, there’s no further investigations. There has been no interest in creditor funding.’
(h) ‘If Goshawk [Mining] is not willing to fund me to obtain a quote from a lawyer, and is also not willing to go with a lawyer of my choosing, then that is where the matter ends ... we will probably shortly file our reports to ASIC ... then finalise the liquidation. If someone’s not coming forward shortly, then it’ll be another three months and it’s over.’
(i) ‘I suggest that the cause of action you have set out in your letters is a cause of action but not one that’s available to me ... that’s not something I could assign to you.’
35 He elaborated in his second affidavit:
In addition to the statements of Mr Bailey set out at paragraph 78 of my affidavit affirmed 26 June 2026 (being my first affidavit in this proceeding), at the 5 June Meeting, Mr Bailey, Mr Hagon and Mr Wilson said words to the following effect:
(a) Liam Bailey: “Public examinations always cost at least $100,000. There would be 6 examinees for this liquidation of Hellyer Metals, off the top of my head, without thinking who’s involved from the Celestial [Group] side ... that’s probably closer to $200,000.”
(b) John Wilson: “Has there been any interest in creditor funding, outside of Goshawk [Mining]/Saxby Capital?”
(c) Liam Bailey: “No.”
(d) John Wilson: “What’s the timeline around this, Liam? We’ve obviously mentioned on a number of occasions, the urgency, given there’s a real risk that Hellyer Gold loses its mining license ... I’m sure you’re across that. What would the proposed timeline be, if you were funded?”
(e) Liam Bailey: “If I was funded, we’d get a quotation together, a funding agreement, and put it to the creditors, or if that was not possible, get approval by the Court. Once that happens, I’d put together the brief to conduct the public examinations, the first part would take 5-6 weeks, the second part would take another month, it would take about another 6 weeks to get the notices to produce back, then there is the Court’s timeline ... the public examinations would be unlikely to occur this year.”
(f) Carl Hagon: “Yeah, particularly if you want the public examinations to be conducted 5 days in a row.”
(g) Liam Bailey: “Yeah. I imagine those public examinations would be towards the start of next year.”
(h) John Wilson: “When would you need a decision by?”
(i) Liam Bailey: “Within the next 6 weeks.”
36 In cross-examination, Liam Bailey was unable to dispute either account.
37 On 26 June 2026, this proceeding was commenced. On 7 July 2026, Carl Hagon corresponded with John Wilson and advised that he had been appointed to act for the defendants. He put various arguments as to why the proceeding lacked merit, asserted that no offer of funding had been made by the plaintiffs, nor had any offer been made to acquire any causes of action that Hellyer Metals may have in respect of the Transaction and concluded with an open offer that the application be withdrawn with no order as to costs, which was open for acceptance until 30 minutes prior to the first case management hearing.
38 On 21 August 2026, solicitors acting for the defendants in the Supreme Court proceedings gave notice that they would make application to discharge the Freezing Order.
39 On 28 August 2026, Liam Bailey signed a litigation funding agreement with Gibraltar Capital Pty Ltd. Recital C provides:
The Liquidator proposes to conduct public examinations in relation to [Hellyer Metals], including examinations of persons with, or potentially with, knowledge of the affairs of or in relation to [Hellyer Metals], the Subsidiaries and the Transferred Subsidiaries and such other persons as may be required.
40 Funding up to $130,000 is provided for professional costs and disbursements for the steps in cl 2.1:
(a) Application to Wind Up Subsidiaries:
(i) instructing solicitors to advise and take steps in proceedings to advance the steps below;
(ii) preparing and filing the application(s) to wind up the Subsidiaries.
(iii) briefing counsel and instructing solicitors for the Applications to Wind Up the Subsidiaries;
(iv) liaising with the Court and obtaining listing and procedural directions for the Applications to Wind Up the Subsidiaries;
(v) preparing, issuing and serving supporting affidavits and other documents required for the Applications to Wind Up the Subsidiaries, including service on relevant persons;
(vi) taking incidental steps reasonably required to complete (b)(v) to (iv), including reasonable adjournments and compliance with Court directions; and
(b) the Public Examinations including:
(i) preparing and filing the application(s) for Public Examinations;
(ii) briefing counsel and instructing solicitors for the Public Examinations;
(iii) liaising with the Court and obtaining listing and procedural directions for the Public Examinations;
(iv) preparing, issuing and serving summonses, supporting affidavits and other documents required for the Public Examinations, including service on examinees and relevant third parties;
(v) conducting the Public Examinations, including attendance by the Liquidator's solicitors and counsel, and obtaining transcripts;
(vi) taking incidental steps reasonably required to complete (v) to (v) (sic), including reasonable adjournments and compliance with Court directions; and
(c) to the extent the Liquidator considers it reasonably necessary:
(i) preparing and filing any application to pool the liquidations of the Company and any of the Subsidiaries and/or Transferred Subsidiaries;
(ii) preparing and filing any application(s) to join or include Related Companies to the Company in Liquidation with respect to any winding up application, and/or in connection with the Public Examinations;
(iii) doing all things necessary to maintain the freezing orders entered in the Supreme Court Proceedings, including but not limited to any interlocutory application to maintain those orders.
41 Adverse costs orders are excluded from the funding by cl 2.3. The funding is non-recourse, with the funder’s entitlement to recovery limited to the proceeds of any claim: cl 7. An unusual aspect of the arrangement is that no commission or uplift is payable.
42 A further unusual aspect is the background to the negotiation of the funding agreement, which Liam Bailey explained in cross-examination. Bradley Monks and Rodger Johnston are former directors of Hellyer Metals. Pieman Resources, Hellyer Gold and Hellyer Metals in proceedings in this Court obtained default judgments against each respectively of $5,238,965 and $2,880,000 in January 2025: see generally Monks v Pieman Resources Pty Ltd [2025] FCAFC 121. Bankruptcy notices were then issued. Bradley Monks and Rodger Johnston applied to set the notices aside, which applications failed and their estates were subsequently sequestrated.
43 Liam Bailey in his capacity as the liquidator of Hellyer Metals, was approached by solicitors acting for Bradley Monks and Rodger Johnston in an endeavour to negotiate a settlement of the amounts owed with the objective of obtaining an annulment of each bankruptcy. Specifically, the proposal was that Liam Bailey would be funded, adopting his evidence, to assume “a more analytical, commercial, unemotional view” in exercising his right to vote in favour of a composition or arrangement pursuant to s 73 of the Bankruptcy Act 1966 (Cth). Liam Bailey decided to “take advantage of the offer” and negotiated an expansion of the proposed funding to facilitate his investigation of the affairs of Hellyer Metals.
44 Liam Bailey’s opportunistic decision to take advantage of a funding offer made for a different purpose raises real issues of how he may prioritise the application of the funds. There is an obvious conflict between acting in the best interests of the creditors of Hellyer Metals and the personal interests of the bankrupt former directors. How the funding was obtained lacks transparency. On Liam Bailey’s evidence there is a side deal to the effect that if he is appointed as liquidator of the subsidiaries, then he will act pragmatically and commercially in a way that may be of advantage to the bankrupt directors. That arrangement raises another conflict of interest issue. It is of particular concern that although Liam Bailey is funded for that purpose, it is not identified as a funded step. There is also a large question as to why he pursued this option, contrary to his undertaking given during the meeting of 5 June 2026, to advise the plaintiffs if he received any other funding proposal.
45 On 10 September 2026, the plaintiffs deposited $200,000 into the trust account of Groom Kennedy Lawyers for the purposes of providing funding to Adam Johnston as liquidator if the removal application succeeds and he is appointed.
46 On 10 September 2026, the defendants in the Supreme Court proceeding made application to discharge the Freezing Order. That application was listed to be determined on 30 September 2026 but was not heard on that day. Presently it stands adjourned for hearing to 1 February 2027.
47 Liam Bailey has not acted consistently in his position on the discharge application. The interlocutory application and affidavit in support were served by email from Bartley Cohen Lawyers to Carl Hagon’s firm, Rostron Carlyle Lawyers, on 28 September 2026 at 1.58 pm. On 29 September 2026, Baxter Bloore, a solicitor at Rostron Carlyle Lawyers, replied by email to Bartley Cohen and said:
We advise that the position is to neither consent nor oppose the below.
48 However, by 30 September 2026, Liam Bailey had appointed HFK Lawyers to act for Hellyer Metals in the Supreme Court. His position on the discharge application altered. HFK Lawyers then corresponded with Page Seager Lawyers who were the agents of Bartley Cohen and the solicitors on the record for the defendants, apart from Hellyer Metals. In a letter dated 30 September 2026, but not emailed until 1 October 2026 at 2.15 pm, they stated:
On a without admissions basis, the Liquidator is presently undertaking investigations into the affairs of [Hellyer Metals] pursuant to his duties under the Corporations Act 2001 (Cth), including in relation to potential voidable transactions, insolvent transactions and dealings between [Hellyer Metals] and associated entities.
On the basis of material reviewed to date, the Liquidator has reason to suspect that there may have been dealings between [Hellyer Metals] and your clients, or entities and persons associated with your clients, concerning assets of [Hellyer Metals], or assets that may properly form part of the property of [Hellyer Metals], and be made available to creditors.
Those matters remain open for investigation, and enquiries in that regard are continuing. In those circumstances, the Liquidator has a direct interest in ensuring that assets held by your clients are not dissipated pending completion of those investigations and is presently taking advice on his being heard on the Discharge Application.
49 Next, Liam Bailey sought an undertaking which HFK Lawyers expressed as:
To avoid the need for our client raising opposition the orders your client seeks on the Discharge Application and to preserve the status quo whilst investigations continue, our client, on a without prejudice and without admissions basis, an undertaking from each of your clients, in a form satisfactory to our client, on the following terms:
Each of the Second Respondent to the Sixth Respondent in proceeding number 3602 of 2023 of the Supreme Court of Tasmania undertakes to the Supreme Court of Tasmania and to the Liquidator, that it will not (until further order of the Supreme Court of Tasmania, or until claims open for investigation in the liquidation of the Hellyer Metals Pty Ltd (In Liquidation) ACN 662 575 073 are resolved or otherwise released by the Liquidator in writing) sell, diminish the value of, dispose of, encumber, or otherwise deal with any of its assets, whether in its own name or otherwise, and whether within or outside Australia, otherwise than in the ordinary and proper course of its business.
The undertaking is to be provided on the basis that it does not constitute an admission of liability by your clients and is provided without prejudice to your clients’ position on the Discharge Application. If you propose amendments to the form of words, including in relation to assets required in the ordinary course of business, please provide your proposed wording for our consideration.
50 Absent agreement to give the undertaking, HFK Lawyers stated that Liam Bailey would oppose the discharge application, file evidence in support of that position and seek costs.
51 There is no evidence that the undertakings have been given. Liam Bailey did not provide supplementary affidavit evidence about his change of position. When asked about this in cross-examination, he departed from the HFK Lawyers correspondence commencing with the Bartley Cohen email of 28 September 2026:
Do you know who Bartley Cohen are? Are they acting for the second to sixth defendants in the matter?---I believe that’s right, yes.
And they’re attaching a copy of the interlocutory application – or Ms Churchill is attaching a copy of the interlocutory application and the supporting affidavit. You’ve read those documents, have you? You’ve read the affidavit of Mr Cohen?---I've read the affidavit, yes.
You have?---Yes.
Right. Now then, if we look at page 1599, there’s an email from Baxter Bloore to Ms Churchill dated 29 September 2026, stating that the position – that’s your position, is – it is to neither consent to nor oppose the discharge?---Correct.
That’s your position, is it?---Correct.
Why would you not oppose an application to discharge an order that is – that freezes the assets which were transferred under the November arrangement?---For a couple of reasons. The first is that, as the liquidator of Hellyer Metals, I’m subject to the freezing order. I’m not sure it's appropriate for me to be consenting or opposing when I’m a party that is subject to the freezing order. It’s not material. It’s not – the freezing order is not there for my benefit. Secondly, it’s my understanding that, in opposing the application, there’s potential to be exposed for costs, and thirdly, in circumstances where there were other avenues to explore to secure – ultimately secure those assets by ultimate means that were appropriate, it was to pursue those. Those being to seek the undertakings of the parties. Or otherwise, through the application for public examinations – there are provisions to obtain freezing orders for the subjective assets relevant to the examinations.
You said that the freezing orders were not to your benefit. Is that right?---They are – they are claimed by clients against - - -
You said - - -?--- - - - Hellyer Metals. So Hellyer – Hellyer Metals did not apply for a freezing order.
No, my question to you was that you – just wanting to confirm what you said a moment ago that, in your view, the freezing orders were not to your benefit?---It's – not in the context that that is put. In terms of benefit, it’s a – as I understood it, or as advised, it’s a legal construction.
The freezing orders were for the benefit of the creditors of Hellyer Metals, weren’t they?---They were for the benefit of your clients – of one of the creditors, yes.
Do you accept that the freezing of these assets was in the interests of and for the benefit of creditors of Hellyer Metals?---Yes.
But you didn’t think that was a relevant consideration. You thought the relevant consideration was whether it was in your interests?---I – that’s a relevant factor, yes.
Well, I suggest to you that is a complete misunderstanding of your role as a liquidator of Hellyer Metals, that your interest is in the interests of the creditors of Hellyer Metals – protecting their interests, and where there is a conflict between your interests and the interests of Hellyer Metals – and the interests of the creditors of Hellyer Metals – the creditors of Hellyer Metals’ interests prevail. Do you agree?---No.
HIS HONOUR: Sorry, you said no?---I said no. I’m not required to take on risk or incurred costs where I’m not funded or protected from doing so.
MR GALVIN: I’m – just to be perfectly clear, this is a very serious matter, Mr Bailey. You do not regard the interests of the creditors of Hellyer Metals as superior to or prevailing over your interests?---No.
52 In re-examination, Liam Bailey was invited to explain what he meant by his interests and those of the creditors:
Now, you gave evidence just before the adjournment about circumstances in which you would put your interests ahead of the interests of creditors. When do you say you can do so?---In circumstances where a particular action required or asked of me would expose me to potential personal costs orders, penalties, etcetera, from which I’m neither funded nor indemnified against. In those circumstances, where I have a personal exposure as a result of the actions I’m required to undertake, I don’t believe that I am required to undertake those actions for the benefit of creditors and put my own personal financial position at risk.
53 There was no re-examination directed to the HFK Lawyers correspondence. Liam Bailey was not confused in his oral evidence. His assessment is that the Freezing Order is not to his benefit, he will not expose himself to the possibility of an adverse costs order and he considers “other avenues” as more appropriate. He has not offered any explanation for the radical departure from his communicated position on 30 September 2026. However, even if that conclusion is wrong and Liam Bailey was confused in his evidence, that does not instil confidence in his ability to competently act in the best interests of the creditors of Hellyer Metals.
54 Very recently, on 14 and 20 October 2026, Liam Bailey applied to wind up the subsidiaries and for the issue of summonses to attend public examinations.
55 There is one further evidentiary matter. Liam Bailey was ordered to make discovery of several documents relating to the administration. One document produced is a work-in-progress record of time spent, and corresponding charges incurred in undertaking investigations. The time recorded commences on 23 January 2026 and concludes on 4 May 2026. There are high level entries identifying the individuals who undertook general investigative work, without much particularisation of the work performed. The total hours spent is 30.35, and the amount to be billed is $14,894.50. I emphasise that this record relates only to investigations, not the general administration of the affairs of Hellyer Metals.
56 Liam Bailey’s affidavit of 28 August 2026 is light on detail about what investigative work has been undertaken. At [46] he says:
Between my appointment as liquidator on 22 January 2026 and the issue of the Statutory Report on 22 April 2026, I also undertook the following additional investigations into the Transaction:
(a) conducted searches of the records available on the registers mainatained (sic) by the Australian Securities and Investments Commission to map out the corporate structure of the Hellyer Group before and after the Transaction;
(b) reviewed the management accounts of [Hellyer Metals] maintained in Xero;
(c) reviewed documents provided to me by Mr Adolfsson, Mr Cox, Mr Bates, Ms Horrocks and others in an effort to verify the information provided by them in the interview on 19 February 2026;
(d) reviewed documents filed in the proceedings commenced by the plaintiffs against the Company in the Supreme Court of Tasmania;
(e) reviewed documents filed in bankruptcy proceedings against former directors of [Hellyer Metals]; and
(f) obtained copies of publicly available documents relating to the mining operations conducted by the Hellyer Group as well as the extensive reports available through online media sources as to the history of the Hellyer Group and its affairs.
57 In cross-examination, he did not provide any more detail. These are generic steps. There is no evidence of any real activity between 4 May 2026 and the commencement of this proceeding, and not much was done before then.
The basis for the removal application
58 It is uncontroversial that s 90-15 of the Insolvency Practice Schedule (Corporations), being Sch 2 to the Corporations Act (IPS), grants plenary power with respect to external administrations: Starbelle Energy Pty Ltd v Louttit (Liquidator), in the matter of Coal Contractors Pty Ltd [2014] FCA 1172 at [22] (Jackman J); In the matter of Columbia Holdings Pty Ltd [2017] NSWSC 1859 at [3] – [6] (Brereton J). The principles that guide the discretion to remove a liquidator were summarised by O’Callaghan J in Gadsden v MacKinnon (Liquidator), in the matter of Allibi Pty Ltd (in liq) [2023] FCA 647 at [74] – [86]. Section 90-15(4) lists matters that may be taken into account, including whether the liquidator has faithfully performed his or her duties.
59 Prior to commencement of the trial, the parties agreed on a list of 16 issues in dispute requiring determination. Fortunately, counsel reduced the issues to:
(1) Do the plaintiffs have standing?
(2) Do the interests of the administration generally favour removal and replacement of the liquidator on the grounds of, if not actual lack of impartiality, an appearance of lack of impartiality?
60 I proceed accordingly.
Standing
61 Section 90-20 of the IPS limits who may apply for orders under s 90-15, relevantly for present purposes, to “a person with a financial interest in the external administration of the company”. Mr Notley submits for Liam Bailey that the plaintiffs as contingent creditors with disputed claims in the administration do not have such interest. His arguments commence with the definition at s 5-30:
Persons with a financial interest in the external administration of a company
A person has a financial interest in the external administration of a company:
(a) if the person is one of the following:
(i) the company;
(ii) a creditor of the company;
(iii) an external administrator of the company;
(iv) in a members' voluntary winding up – a member of the company; or
(b) in any other circumstances prescribed.
62 There are no prescribed circumstances. As developed, the submissions highlight the reference to “a creditor of the company” at subparagraph (ii) in contradistinction to the multiple references to creditors elsewhere in Part 5.3A of the Corporations Act. Those references are relevantly confined by s 459P (who may apply for a winding up order) and s 462 (standing to apply for a winding up order), and do not extend to contingent and prospective creditors. Reliance is placed on Treadtel International Pty Ltd v Cocco [2016] NSWCA 360; (2016) 316 FLR 318 at [47] – [50] and [57] – [58], Barrett AJA (with whom Gleeson and Leeming JJA agreed).
63 I reject the submission. Treadtel concerned an application to amend a claim in an oppression proceeding pursuant to Part 2F.1 of the Corporations Act. The primary judge allowed an amendment to include an application to wind up pursuant to s 462, holding that it was arguable that the claimant was a creditor based on an unliquidated claim for damages: Re Treadtel International Pty Ltd (No 2) [2016] NSWSC 791.
64 The respondents applied for leave to appeal, contending that the primary judge erred on the issue of standing of the claimant as a creditor within the meaning of s 462. The Court of Appeal granted leave and allowed the appeal on that point. Barrett AJA relevantly reasoned that although a claim for damages is by s 553(1) provable, it does not follow that an untested claim for damages confers standing to make a winding up application: [48]. His Honour comprehensively considered the case law (which was not then consistent) commencing at [49] to hold in part at [57] – [58]:
The view to be taken of a contingent or prospective creditor will, in my opinion, differ according to the purpose for which the creditor’s position is under consideration. Recognition as someone qualified to be heard on another applicant’s winding up petition or as someone whose claim should be taken into account in judging solvency is one thing. Recognition as someone who may initiate winding up proceedings is another. It is a well-established rule of practice that a person who claims to be a creditor but whose debt is disputed on genuine grounds will not be permitted to initiate or pursue a winding up application.
…
The rationale of the several decisions I have mentioned concerning contingent and prospective creditors is, it seems to me, that such a creditor will not be permitted to apply for winding up unless there is an existing obligation of the company (as required by the decision in Community Development Pty Ltd v Engwirda Construction Co), which obligation can be viewed with a high degree of assurance as a source of financial liability. Thus, in a case such as Re PMC Investments Pty Ltd, a defaulting purchaser under a conveyancing transaction may be seen to be subject to a relevant obligation where the standard contractual position is uncontroversial and the value of the property is shown to be such that the default has occasioned loss to the vendor, even though no proceedings for damages have crystallised that liability. But the position is otherwise where, as in Thomas v Mackay Investments Pty Ltd, the existence of the obligation, as well as the quantification of any damage, is dependent on the resolution of disputed or otherwise unclear legal rights and duties by means of proceedings for damages brought against the company.
(Citations omitted.)
65 With respect to the careful argument of Mr Notley, the reasoning of Barrett AJA does not support the submission on the straightforward basis that there is a distinct difference between the standing of a creditor to make a winding up application and the ability to lodge a proof of debt in the administration of an insolvent corporation, which pursuant to s 553, extends to claims that are “present or future, certain or contingent, ascertained or sounding only in damages”.
66 The policy objective that this provision secures is to achieve a pari passu distribution of the available assets: Re Jay-O-Bees; Rosseau v Jay-O-Bees [2004] NSWSC 818; (2004) 50 ACSR 565 at [89], Campbell J. There is no textual, contextual or policy purpose in narrowly construing the reference to a creditor of the company, in the definition of a person who has a financial interest in the external administration at s 5-30 of the IPS, as excluding contingent creditors with claims sounding only in damages, similarly with the reasoning of the Victorian Court of Appeal when construing the binding effect of a deed of company arrangement at s 444D: Brash Holdings Ltd v Katile Pty Ltd [1996] 1 VR 24 at 31 – 32.
67 Goshawk Mining and Saxby Capital were entitled to lodge their proofs of debt in the winding up and it follows that they each have a financial interest in the external administration of Hellyer Metals.
Impartiality
68 I do not determine the case of actual impartiality as I am well satisfied that the plaintiffs’ case of apprehended impartiality is made out. The applicable principles were set out by the Full Court (when considering the former power at s 503 of the Corporations Act) in Australian Securities and Investments Commission v Franklin [2014] FCAFC 85; (2014) 223 FCR 204, Jessup, Robertson and White JJ. White J gave the lead judgment on apprehended bias. The Ebner v Official Trustee in Bankruptcy [2000] HCA 63; (2000) 205 CLR 337 test at [6] applies: [59]. His Honour continued at [60]:
The “double might” test stated in Ebner has been regarded as relatively undemanding and, on occasion, has been described as “Spartan”. Nevertheless, the degree of independence and impartiality to be expected of a decision maker may differ from one statutory context to another. As Spigelman CJ observed in McGovern v Ku-ring-gai Council [2008] NSWCA 209 at [11]; (2008) 72 NSWLR 504 at 508, “the judicial paradigm is not universally applicable”. Similarly, this Court observed in Cabcharge Australia Ltd v Australian Competition and Consumer Commission [2010] FCAFC 111 at [27] that, “although the test for apprehended bias is ordinarily the same wherever it arises, the precise language used in applying the test has frequently varied depending on the context in which it falls to be applied”. This means, in the present case, that particular regard must be had to the position of liquidators in a voluntary winding up.
69 The application of the principle requires: (1) identification of the matters that might lead the fair-minded lay observer to apprehend that Liam Bailey is not impartial; (2) articulation of the logical connexion to the apprehension; and (3) the assessment of the reasonableness of the apprehension: QYFM v Minister for Immigration, Citizenship and Multicultural Affairs [2023] HCA 15; (2023) 279 CLR 148 at [38], Kiefel CJ, Gageler J.
70 The fair-minded lay observer must be imputed with knowledge of the essentiality of independence by a liquidator: Re Allebart Pty Ltd [1971] 1 NSWLR 24. Although that case concerned a court appointed liquidator, no different principle applies to an appointee by resolution of the members. Street J observed at 28 and 30:
A liquidator is bound to be on guard lest he compromise his position of independence and impartiality in all respects in the discharge of his functions as an officer of the court administering the winding up of a company. Not only is it his prerogative to decide what steps should be taken, but it is his duty to exercise himself, according to the dictates of his own opinions, what should and what should not be done in the course of any given winding up. It is for him to decide what steps are to be taken, and when, how and by what means such steps are to be taken. Where he draws upon financial assistance from a creditor, it is incumbent upon him to ensure that he does not place in jeopardy his independence in the discharge of his duties. It is indispensable that in point of substance the liquidator’s independence should be preserved; and it is undesirable that a liquidator should permit a situation to develop in which it might appear that he has yielded up in any degree whatever his exclusive independent control in the decision-making processes and administration of a winding up.
…
It is essential that the independence and impartiality of a liquidator should at all times exist in point of substance, and be manifestly seen to exist.
71 There are several matters that the plaintiffs rely on as founding their apparent lack of impartiality case. From commencement of the Goshawk Mining proceeding on 22 December 2023, Hellyer Metals faced a potentially very large claim for damages. Thereafter, commencing in October 2025, steps were put in place that ultimately resulted in the Transaction whereby Hellyer Metals was denuded of its assets without apparently receiving valuable consideration from Celestial Group. This caused the plaintiffs to make application for and ultimately obtain the Freezing Order on 2 December 2025. Shortly thereafter, on 22 January 2026, Liam Bailey was appointed as the liquidator pursuant to the voluntary winding up procedure. The persons responsible for the appointment were Graham Cox, Alan Bates and Karl Adolfsson.
72 The solicitor, Carl Hagon, first approached Liam Bailey to introduce each of those gentlemen for the purposes of a creditors’ voluntary winding up. Thereafter, Carl Hagon accepted a retainer to act for Liam Bailey in connection with the matters raised by the plaintiffs, and subsequently in this proceeding. The selection by Liam Bailey of Carl Hagon as his solicitor is significant. It was Carl Hagon who put the directors of Hellyer Metals in contact with Liam Bailey, and who, in his email of 7 May 2026 to Marisa Gillam, stated that those directors disputed the plaintiffs’ status as creditors.
73 Alan Bates controls Gaston Resources which held approximately 95% of the shares in Hellyer Metals. He indirectly owns all the shares in Celestial Group. Celestial Investments wholly owns Celestial Group, and Celestial Group wholly owns Celestial Metals. Thus, the persons responsible for appointing Liam Bailey are the individuals behind the Transaction that the plaintiffs have urged Liam Bailey to urgently investigate since 27 February 2026. Liam Bailey then chose to appoint Hagon as his solicitor to deal with the plaintiffs’ concerns. These matters raise acute questions of a lack of independent judgment by Liam Bailey.
74 The course of correspondence, commencing with the detailed letter from John Wilson to Liam Bailey of 27 February 2026, and thereafter between Groom Kennedy Lawyers, Liam Bailey and/or Carl Hagon until the commencement of this proceeding on 26 June 2026, evidences a failure by Liam Bailey to grasp the urgency of moving with alacrity to investigate the Transaction. It is further evidence of his failure to meaningfully engage with the plaintiffs to secure adequate funding for an investigation of the circumstances of the Transaction. The willingness of the plaintiffs to provide funding, on terms to be agreed, was clearly communicated in the correspondence from Groom Kennedy Lawyers on 17 and 27 March and 6 May 2026. Liam Bailey failed to satisfactorily engage with those invitations. Instead, and contrary to the undertaking he gave on 5 June 2026, he entered into the funding agreement with Gibraltar Capital on 28 August 2026. The circumstances of that funding give rise to further concerns in that the agreement post-dates the commencement of this proceeding and resulted from an approach by solicitors acting for Bradley Monks and Rodger Johnston, whose interests in reaching a composition with their creditors do not align with the need to investigate the Transaction. The funding agreement is opaque as to the real purpose that sits behind it, namely future steps that may assist the bankrupt directors. Liam Bailey is clearly conflicted in determining how the funding is allocated between the public examinations, the winding up of the subsidiaries and assistance to the bankrupt directors. Further, the funding is modest and the absence of commercial return for Gibraltar Capital remains unexplained.
75 On 17 March 2026, Carl Hagon represented in his email to John Wilson that Liam Bailey “is presently undertaking investigations regarding the various causes of action available to him. As set out below, those investigations are not complete”. In cross-examination, Liam Bailey admitted it was possible he was not then undertaking any investigations because he had the care of his newborn infant and accepted that his staff “were not doing anything at all in relation to these transactions”. He also accepted that another statement in that email that: “our client has obtained the full cooperation of the all (sic) related entities and has interviewed them and requested, and been provided with, all necessary documents” was false. He had not obtained the full cooperation of the directors and had not been provided with all relevant company records.
76 Liam Bailey did not utilise his powers at ss 530A, 530B and/or 530C of the Corporations Act to obtain the financial and other records of Hellyer Metals. In particular he failed to exercise these powers to obtain the accounting records from Xero. His evidence was that he requested the passcode for the Xero database from the directors, they told him that they would provide it but that they failed to do so. Still, he took no step to obtain access to the accounting records.
77 The Statutory Report of 22 April 2026 was provided in draft to the directors of Hellyer Metals and the former General Counsel, Ms Horrocks. These are the very people intimately involved in the Transaction. They were invited to comment on the draft and Ms Horrocks did so. Whether her comments were accepted or not is not to the point. The Statutory Report in section 8 outlined Liam Bailey’s understanding of the Transaction, his assessment that Celestial Group did not provide valuable consideration for the share transfers and the need to undertake further investigations. Any proceedings commenced following the investigation would inevitably have named the former directors and/or Ms Horrocks as respondents, for breach of director and officer duties. Objectively, they should not have been afforded the opportunity to review and comment on the draft. That was a serious error of judgment and demonstrative of a lack of independence.
78 In section 8.2.9 (iii) of the Statutory Report, Liam Bailey stated:
It seems very likely that any action commenced avoid the transfer of the collective assets of the Hellyer Group to Celestial [Group] would likely destroy the value in those assets, noting the value seems to be in the continuing operations of the Hellyer Project operated by Hellyer Gold.
79 This betrays one of the fundamental obligations of Liam Bailey as liquidator of Hellyer Metals: to investigate questionable transactions, commence recovery proceedings where there is a proper basis to do so with the objective of getting in assets for the benefit of creditors: Re Allebart at 26 – 27. Liam Bailey’s duty most certainly was not to preserve the value of the assets in the hands of Celestial Group. If a risk of recovery proceedings was devaluation of the trading assets, that would not have impacted the personal liability of directors and other officers of Hellyer Metals for breach of the range of duties at ss 180, 181, 182 or 183 of the Corporations Act.
80 Further, the Statutory Report at (iv) of the same section noted that to “advance any claims for the recovery of assets or against the Directors”, Liam Bailey would require significant funding. He invited creditors to contact him to discuss funding. He failed to mention the willingness of the plaintiffs to engage in funding discussions.
81 The Freezing Order is protective of the interests of the creditors. Liam Bailey has either departed from the position stated in the HFK Lawyers correspondence of 30 September 2026 or he is genuinely confused and uncertain as to what his position is, each of which raises matters of concern about his independent judgment.
82 The statements made by Liam Bailey during the meeting of 5 June 2026 raise issues of fundamental concern. He claimed no ability to obtain relevant records from Hellyer Metals Underground, Hellyer Gold or Celestial Group absent an application for the issue of summonses for a public examination. The fact is that he had not exercised that power until after commencement of this proceeding. He claimed to be hamstrung by a lack of funding but had not engaged meaningfully with the plaintiffs’ funding proposal. He objectively demonstrated his lack of enthusiasm to investigate by advising that if Goshawk Mining was unwilling to provide funding, then he would “probably shortly file our reports with ASIC, then finalise the liquidation”, and if funding was not forthcoming “shortly, then it will be another three months and it’s all over”. He said those things when analysis of his work-in-progress ledger reveals very little was done to engage with possible funders between 23 January 2026 and 4 May 2026: that is, of the 30.35 hours recorded in that period there is only one entry about discussing litigation funding on 2 February 2026 recorded at 0.20 hours (that is 12 minutes) at a charge of $140.
83 Overall, there has been very little investigative activity undertaken by Liam Bailey and/or his staff since 23 January 2026. I have noted the work-in-progress ledger to 4 May 2026. Thereafter, the affidavit of Liam Bailey of 28 August 2026 at [46], is unhelpful in that it makes general claims without particulars and the evidence in cross-examination was unilluminating. It was not until after the commencement of this proceeding that Liam Bailey took some action, by obtaining funding from Gibraltar Capital and applying for the issue of summonses for public examinations.
84 There is also the troubling evidence that Liam Bailey gave in cross-examination to the effect that he did not regard the interests of the creditors of Hellyer Metals as superior to or prevailing over his own. Even with the qualification in re-examination (what he meant was in circumstances where he was exposed to personal costs orders or penalties) his evidence is concerning. The question in cross-examination related to his decision to neither consent to nor oppose the application to discharge the Freezing Order. He answered that in his view he was not required to accept risks or to incur costs without funding. Clearly, he had in mind s 545 of the Corporations Act:
Expenses of winding up where property insufficient
(1) Subject to this section, a liquidator is not liable to incur any expense in relation to the winding up of a company unless there is sufficient available property.
(2) The Court or ASIC may, on the application of a creditor or a contributory, direct a liquidator to incur a particular expense on condition that the creditor or contributory indemnifies the liquidator in respect of the recovery of the amount expended and, if the Court or ASIC so directs, gives such security to secure the amount of the indemnity as the Court or ASIC thinks reasonable.
85 Mr Notley draws attention to Jahani, in the matter of Ralan Group Pty Ltd (in liq) [2022] FCA 107; (2022) 159 ACSR 222 at [120] and [122] (Farrell J), and Lucas, in the matter of Filestock Pty Ltd (in liq) [2017] FCA 1425 at [7] (Derrington J), as authority that by reason of this provision a liquidator is not obliged to perform his or her role (save for limited inquiries and lodging statutory reports) where the assets are insufficient to fund that work, absent remuneration or indemnity.
86 Those cases are readily distinguishable. In assessing whether the fair-minded lay observer might reasonably apprehend that Liam Bailey might not be impartial, the issue is why he did not constructively engage with the plaintiffs’ invitations to discuss adequate funding where it is probable that if he had pursued the investigation, funding would have been agreed. The letter from Carl Hagon to John Wilson of 7 July 2026 asserted disingenuously that the plaintiffs had “not made a single offer to fund our client to take any action, be it public examination or otherwise”. He then distinguished between an offer and an invitation to treat. But as Liam Bailey accepted in cross-examination, he did not advise the plaintiffs how much funding might be required and did not provide an estimate of the costs to undertake public examinations.
87 Also, Mr Notley’s submission overlooks the context in which Liam Bailey decided not to participate in the discharge application. First, Liam Bailey secured the Gibraltar Capital funding on 28 August 2026. Clause 2.1(c) extends that funding to steps that he reasonably considers necessary to “maintain the freezing orders”. He therefore has funding to engage lawyers to oppose the discharge application, although cl 2.3 of the funding agreement excludes any liability for adverse costs orders.
88 Second, two amounts of security have been paid into court: $578,000 by Goshawk Mining and $322,000 by Hellyer Metals. Liam Bailey’s evidence, in answer to a question from me, is that the funds remain in court. If Liam Bailey were to oppose the discharge application to protect the interests of the creditors of Hellyer Metals, then in the event that the Freezing Order is discharged, the first recourse to satisfy any costs orders made in favour of Hellyer Gold, Hellyer Metals Underground, Celestial Group, Ivy Resources and/or Keen Pacific would be the security provided by Hellyer Metals. That sum is clearly adequate costs protection if Liam Bailey determined to oppose the discharge application, effectively as contradictor.
89 Third, there is a proper basis to reasonably assume that if Liam Bailey did adopt the role as contradictor to oppose the discharge application and was unsuccessful, that costs would be ordered from the security provided by Goshawk Mining as the entity that obtained the benefit of the Freezing Order.
90 Objectively, the fair-minded observer would be concerned to understand what a reasonable liquidator would have done conformably with s 180 of the Corporations Act (and the corresponding duty at common law) in this matter. For more than eight months Liam Bailey has had the benefit of a detailed analysis of the Transaction from Groom Kennedy Lawyers which manifestly warranted urgent investigation where the plaintiffs offered to engage in constructive discussions to provide funding. However, he largely failed to act until after the commencement of this proceeding. A reasonable liquidator in the like position would have acted with more haste, would have exercised the available statutory powers to obtain documents, would have constructively engaged in funding discussions with the plaintiffs and would most likely have reached early agreement to fund and then commence the process of public examinations. A duty with that content in the circumstances of this case aligns with the general duty of a liquidator “to carry out reasonable investigations into potential claims so as to form an opinion as to what future course of action is in the creditors’ interests”: Independent Cement and Lime Pty Ltd v Brick and Block Co Ltd (in liq) [2010] FCA 352; (2010) 267 ALR 613 at [49], Finkelstein J.
91 I accept that removal of a liquidator is a discretion not lightly exercised and will only be made if in the best interests of the liquidation: Re Gemwood Projects Pty Ltd (in liq) [2025] VSC 819; (2025) 177 ACSR 269 at [205] – [213], Croft J; Gadsden at [79] and [81]; In the matter of ACN 151 726 224 Pty Ltd (in liq) [2016] NSWSC 1801 at [36], Black J. Removal must be warranted for cause. A primary matter is “the need for confidence in the integrity, objectivity and impartiality of the winding up”: Re FW Projects Pty Ltd (in liq) [2019] NSWSC 892 at [86], Black J.
92 Removal is justified, indeed required, in this case. The plaintiffs, who assert they are the largest unsecured creditors by a very large margin, have lost confidence in Liam Bailey. There is an objective basis for that subjective view. Liam Bailey undertook little investigative work prior to the commencement of this proceeding. He was spurred into action because of it. The circumstances that led to the Gibraltar Capital funding are opaque and Liam Bailey faces an acute conflict of interest in deciding how the funds are to be applied.
93 If Liam Bailey has decided neither to consent to nor oppose the application to discharge the Freezing Order, then the interests of the creditors of Hellyer Metals are at substantial risk. The basis for the making of the orders is to prevent frustration of the processes of the Supreme Court by seeking to meet the danger that a prospective judgment will be wholly or partially unsatisfied: Supreme Court Rules 2000 (Tas), r 937B. That risk has not dissipated. The exposure to an adverse costs order justification is not credible.
94 The plaintiffs have deposited substantial funds into the trust account of their solicitor to be held to fund an alternative liquidator. They have since February 2026 repeatedly agitated the need to urgently investigate the circumstances of the Transaction, and if there are reasonable grounds to do so, to commence recovery proceedings under Part 5.7B of the Corporations Act. The Transaction is prima facie highly questionable by reason of the timing, the individuals behind it and the consequence that Hellyer Metals appears to have been stripped of assets for no valuable consideration. The potential recovery for creditors is very substantial. In contrast, the inactivity of Liam Bailey is objectively concerning.
95 Bradley Saxby denied in cross-examination that the plaintiffs have commenced the proceeding with the objective of securing a liquidator who will view more favourably their proofs of debt, which evidence I accept. It is consistent with the position from February to June 2026 that they urged Liam Bailey to act and were prepared to fund an investigation on agreed terms. They have obtained the consent of Adam Johnston, a registered liquidator, to act.
96 Liam Bailey has not undertaken preliminary investigations thoroughly. He has failed to require the directors to provide the assistance required by s 530A of the Corporations Act and has failed to get in all relevant company records by exercise of the power at s 530B. His very recent action in applying for examination summonses and the production of records was most probably in response to this proceeding.
97 There are aspects of the Statutory Report that raise very real questions of impartiality: the reference to winding up by resolution of the sole member, his substantial reliance on information provided by the directors who would be defendants in a Part 5.7B proceeding, his assertion that he lacked authority to review the actions of Hellyer No.1 and his assessment that a recovery proceeding would likely destroy the value of the assets transferred to Celestial Group.
98 The liquidation of Hellyer Metals is still at an early stage, despite Liam Bailey’s appointment on 22 January 2026. A new liquidator with a laser-like focus on the need to thoroughly and quickly investigate the Transaction with adequate funding is in the best interests of the administration.
99 I am satisfied having considered all of these matters that the apprehended lack of impartiality case is made out. There are numerous facts that might lead a fair-minded lay observer to apprehend that Liam Bailey might not bring an impartial mind to the administration of the liquidation. The logical connexion between those facts and the apprehended lack of impartiality is established, and the apprehension is a reasonable one to draw from the perspective of the fair-minded observer.
100 I therefore order that Liam Bailey be removed as liquidator of Hellyer Metals. Adam Johnston of Apex Advisory Australia of Suite 12, 11 Morrison Street, Hobart is a registered liquidator who has provided a consent to act. He has stated that he has no conflict of interest that would make it improper for him to be appointed, nor is he aware of any relevant relationship of the type at s 60(2) of the Corporations Act. I am satisfied that he should be appointed.
101 As to costs, a difference in the plaintiffs’ position emerged late in closing submissions. The Originating Application seeks an order that Liam Bailey pay the costs to be assessed and paid out of the property of Hellyer Metals. In submissions, a personal costs application was formulated. As a matter of procedural fairness Liam Bailey was not given adequate notice of that application. The parties will be given leave to file short submissions on the question of costs.
I certify that the preceding one hundred and one (101) numbered paragraphs are a true copy of the Reasons for Judgment of the Honourable Justice McElwaine. |
Associate:
Dated: 10 November 2026