Federal Court of Australia
Australian Securities and Investments Commission v Keystone Asset Management Limited (receivers and managers appointed) (in liquidation) (No 6) [2026] FCA 1463
File number: | VID 536 of 2024 |
Judgment of: | MOSHINSKY J |
Date of judgment: | 29 September 2026 |
Catchwords: | CORPORATIONS – external administration – where receivers and managers appointed – where company in liquidation – where receivers and managers and liquidators sought judicial advice relating to an interim distribution of funds to unitholders – where unitholders either supported or did not oppose the interim distribution – where interim distribution designed to alleviate hardship to underlying unitholders – judicial advice given |
Legislation: | Corporations Act 2001 (Cth), ch 5C, s 601NE |
Cases cited: | Australian Securities and Investments Commission v Keystone Asset Management Limited (No 3) [2025] FCA 1661 |
Division: | General Division |
Registry: | Victoria |
National Practice Area: | Commercial and Corporations |
Sub-area: | Corporations and Corporate Insolvency |
Number of paragraphs: | 51 |
Date of hearing: | 15 June 2026 and 29 September 2026 |
Counsel for the Plaintiff: | The Plaintiff did not appear |
Counsel for the Receivers and Liquidators: | Dr O Bigos KC with Mr L Freckelton |
Solicitor for the Receivers and Liquidators: | Norton Rose Fulbright Australia |
Counsel for the Contradictors: | Mr JP Moore KC with Ms SM Hooper |
Solicitor for the Contradictors: | Mills Oakley |
Counsel for the Macquarie Parties: | Mr D McAloon SC |
Solicitor for the Macquarie Parties: | Allens |
Counsel for the Second Defendant: | The Second Defendant did not appear |
ORDERS
VID 536 of 2024 | ||
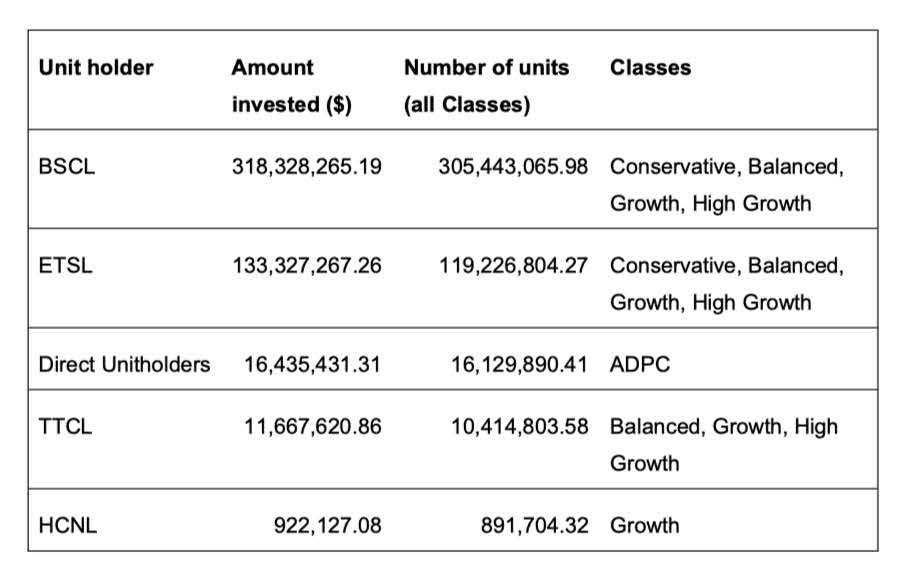
| ||
BETWEEN: | AUSTRALIAN SECURITIES AND INVESTMENTS COMMISSION Plaintiff | |
AND: | KEYSTONE ASSET MANAGEMENT LIMITED (RECEIVERS AND MANAGERS APPOINTED) (IN LIQUIDATION) (ACN 612 443 008) First Defendant PAUL ANTHONY CHIODO Second Defendant | |
order made by: | MOSHINSKY J |
DATE OF ORDER: | 29 SEPTEMBER 2026 |
THE COURT NOTES THAT:
A. These orders are in respect of the application made by paragraphs 4, 5 and 9 of the further amended interlocutory process dated 15 June 2026 filed by the First Defendant, Keystone Asset Management Ltd (ACN 612 443 008) (receivers and managers appointed) (in liquidation) (Keystone) in its capacity as the responsible entity of the Shield Master Fund (ARSN 650 112 057) (Fund), and Jason Tracy and Glen Kanevsky in their capacity as both joint and several receivers of the property of Keystone in all its capacities (Receivers) and joint and several liquidators of Keystone (Liquidators).
B. By paragraphs 3 and 4 of the orders made on 11 December 2025, the Court appointed Ross Blakeley and Paul Harlond in their capacity as joint and several liquidators of Falcon Capital Limited (ACN 119 204 554) (in liquidation) as contradictors and ordered that they be indemnified for their reasonably incurred remuneration and costs (including legal costs) of and incidental to their appointment as contradictors out of the assets held by Keystone in its capacity as responsible entity of the Fund.
THE COURT ORDERS THAT:
1. Pursuant to s 601NF(2) of the Corporations Act 2001 (Cth) (Corporations Act) and s 63 of the Trustee Act 1925 (NSW) (Trustee Act), Keystone is justified and is acting reasonably and properly in:
(a) making an interim distribution of up to $100,186,713.49 from the cash at bank of the Fund (including the net proceeds of realisation and sale of the listed equities that were owned by Keystone as responsible entity of the Fund with Bell Potter Securities Limited (Bell Potter Securities) attributable to each class of the Fund) (Interim Distribution), to the members of the Fund (Unitholders), without paying Expenses (as defined in the Fund’s Constitution) before making the Interim Distribution; and
(b) applying so much of the Interim Distribution which comprises the proceeds of realisation and sale of the Bell Potter Securities attributable to a class of the Fund, among the Unitholders of that class, in proportion to the number of units in that class:
(i) where the Unitholders are shown as the registered holder in the register of unitholders described at paragraph 31 of the affidavit of Jason Mark Tracy affirmed on 7 November 2025, except where the register records persons who the Liquidators and Receivers are satisfied no longer hold units in the fund; or
(ii) the Liquidators and Receivers are otherwise satisfied that the Unitholder holds units in that class.
2. Pursuant to ss 19 and 23 of the Federal Court of Australia Act 1976 (Cth) (Federal Court Act), r 14.23 of the Federal Court Rules 2011, and s 90-15 of the Insolvency Practice Schedule (Corporations) (being Sch 2 to the Corporations Act), the Receivers and Liquidators are justified and are acting reasonably and properly in causing Keystone to make the Interim Distribution in accordance with paragraph 1 above.
3. Pursuant to s 85 of the Trustee Act, Keystone is relieved from any liability for breach of clause 13.29 of the Fund Constitution for issuing “AMMA Statements” to Unitholders for the financial years ended 30 June 2024 and 30 June 2025 after the period of three months from the end of each of those financial years as provided for in clause 13.29 of the Fund Constitution.
4. Pursuant to s 37AF of the Federal Court Act, on the ground in s 37AG(1)(a) of the Federal Court Act, until further order, the redacted parts of the twenty-first affidavit of Jason Mark Tracy affirmed on 24 September 2026 be kept confidential and not be published or accessed except pursuant to an order of the Court.
5. The costs of Keystone and the Liquidators and Receivers of and incidental to their further amended interlocutory process dated 17 June 2026 be costs in the winding up of the Fund.
Note: Entry of orders is dealt with in Rule 39.32 of the Federal Court Rules 2011.
REASONS FOR JUDGMENT
MOSHINSKY J:
Introduction
1 This is an application by Mr Jason Tracy and Mr Glen Kanevsky (the Appointees) of Alvarez and Marsal Australia, the joint and several receivers (in this capacity, the Receivers) and liquidators appointed to the first defendant (Keystone), for directions and judicial advice relating to a proposed interim distribution to unitholders of the Shield Master Fund (the SMF) of approximately $100 million.
2 The present application is made by paras 4 and 5 of the Appointees’ further amended interlocutory process dated 15 June 2026. In addition, by para 9 of that interlocutory process, the Appointees seek an order that Keystone be relieved of liability for breach of clause 13.29 of the SMF’s constitution dated 28 April 2021 (the SMF Constitution).
3 An earlier version of the interlocutory process was the amended interlocutory process dated 8 December 2025. I dealt with paras 1-3 of the amended interlocutory process (which sought judicial advice in relation to the sale of certain securities referred to as the Bell Potter Securities) in reasons for judgment dated 19 December 2025: Australian Securities and Investments Commission v Keystone Asset Management Limited (No 3) [2025] FCA 1661 (the December 2025 Reasons). These reasons should be read together with the December 2025 Reasons. I will adopt the abbreviations used in the December 2025 Reasons.
4 After the orders were made on 19 December 2025, the Appointees sold the Bell Potter Securities, realising approximately $195 million. They now propose an interim distribution of about $100 million.
5 The present application was the subject of an initial hearing on 15 June 2026. The materials filed for the purposes of that hearing indicated that several issues relating to the proposed interim distribution remained unresolved. I indicated that I considered it appropriate for these issues to be resolved before I would make the directions and orders sought by the Appointees. Accordingly, the hearing was adjourned to a date to be fixed, with that date to be determined after the Appointees had filed further material relating to the outstanding issues. The application was subsequently listed for further hearing on 29 September 2026
6 On 11 December 2025, the Court appointed Mr Ross Blakeley and Mr Paul Harlond (the Falcon Liquidators), in their capacity as joint and several liquidators of Falcon Capital Limited (in liquidation), as contradictors in relation to the present application. This was in a context where, at that time, the Falcon Liquidators opposed the proposed interim distribution on the basis of potential claims in relation to the relevant funds. However, subsequently, as a result of further investigations conducted by the Appointees, it became apparent that any such claims were limited to a relatively small sum. Further, the Appointees agreed to retain sufficient proceeds to cover any such claims. As a result, by the time of the hearing on 15 June 2026, the Falcon Liquidators no longer opposed the proposed interim distribution. That remained the position at the hearing on 29 September 2026. The Falcon Liquidators nevertheless made helpful submissions designed to assist the Court at both the hearing on 15 June 2026 and the hearing on 29 September 2026.
7 Macquarie Investment Management Limited (MIML), Macquarie Financial Limited (MFL) and Bond Street Custodians Limited (BSCL) (together, the Macquarie Parties) appeared at the hearing on 29 September 2026 and supported the directions and orders sought by the Appointees.
8 There were no other appearances. In particular, ETSL and Praemium Australia Limited (Praemium), the two other institutional unitholders, did not appear. The materials before the Court indicate that they do not oppose the directions and orders sought by the Appointees. No underlying unitholder appeared (whether in support of or in opposition to the application). The materials indicate that notice has been given in various ways to the underlying unitholders.
9 The Appointees rely on affidavits of Mr Tracy dated 7 November 2025, 29 January 2026, 31 May 2026, 12 June 2026 and 24 September 2026.
10 The Falcon Liquidators filed the following affidavits: two affidavits of Mr Blakeley dated 16 February 2026; and an affidavit of Mr Harlond dated 11 June 2026.
11 The Appointees rely on outlines of submissions dated 10 December 2025, 29 January 2026, 31 May 2026 and 25 September 2026.
12 The Falcon Liquidators rely on outlines of submissions dated 16 February 2026 and 12 June 2026.
13 The form of directions and orders sought by the Appointees are annexed to their outline of submissions dated 25 September 2026. The directions and orders sought are as follows:
THE COURT NOTES THAT:
A. These orders are in respect of the application made by paragraphs 4, 5 and 9 of the further amended interlocutory process dated [15] June 2026 filed by the First Defendant, Keystone Asset Management Ltd ACN 612 443 008 (receivers and managers appointed) (in liquidation) (Keystone) in its capacity as the responsible entity of the Shield Master Fund ARSN 650 112 057 (Fund), and Jason Tracy and Glen Kanevsky in their capacity as both joint and several receivers of the property of Keystone in all its capacities (Receivers) and joint and several liquidators of Keystone (Liquidators).
B. By paragraphs 3 and 4 of the orders made on 11 December 2025, the Court appointed Mr Ross Blakeley and Mr Paul Harlond in their capacity as joint and several liquidators of Falcon Capital Limited (ACN 119 204 554) (in liquidation) as contradictors and ordered that they be indemnified for their reasonably incurred remuneration and costs (including legal costs) of and incidental to their appointment as contradictors out of the assets held by Keystone in its capacity as responsible entity of the Fund.
THE COURT ORDERS THAT:
1. Pursuant to section 601NF(2) of the Corporations Act 2001 (Cth) (Corporations Act) and section 63 of the Trustee Act 1925 (NSW) (Trustee Act), Keystone is justified and is acting reasonably and properly in:
(a) making an interim distribution of up to $100,186,713.49 from the cash at bank of the Fund (including the net proceeds of realisation and sale of the listed equities that were owned by Keystone as responsible entity of the Fund with Bell Potter Securities Limited (Bell Potter Securities) attributable to each class of the Fund) (Interim Distribution), to the members of the Fund (Unitholders), without paying Expenses (as defined in the Fund’s Constitution) before making the Interim Distribution; and
(b) applying so much of the Interim Distribution which comprises the proceeds of realisation and sale of the Bell Potter Securities attributable to a class of the Fund, among the Unitholders of that class, in proportion to the number of units in that class:
(i) where the Unitholders are shown as the registered holder in the register of unitholders described at paragraph 31 of the affidavit of Jason Mark Tracy affirmed on 7 November 2025, except where the register records persons who the Liquidators and Receivers are satisfied no longer hold units in the fund; or
(ii) the Liquidators and Receivers are otherwise satisfied that the Unitholder holds units in that class.
2. Pursuant to sections 19 and 23 of the Federal Court of Australia Act 1976 (Cth) (Federal Court Act), rule 14.23 of the Federal Court Rules 2011 (Cth), and section 90-15 of the Insolvency Practice Schedule (Corporations) (being schedule 2 to the Corporations Act), the Receivers and Liquidators are justified and are acting reasonably and properly in causing Keystone to make the Interim Distribution in accordance with paragraph 1 above.
3. Pursuant to section 85 of the Trustee Act, Keystone is relieved from any liability for breach of clause 13.29 of the Fund constitution for issuing “AMMA Statements” to Unitholders for the financial years ended 30 June 2024 and 30 June 2025 after the period of three months from the end of each of those financial years as provided for in clause 13.29 of the Fund constitution.
4. Pursuant to section 37AF of the Federal Court Act, on the ground in paragraph 37AG(1)(a) of the Federal Court Act, until further order, the redacted parts of the twenty-first affidavit of Jason Tracy affirmed on 24 September 2026 be kept confidential and not be published or accessed except pursuant to an order of the Court[.]
5. The costs of Keystone and the Liquidators and Receivers of and incidental to their further amended interlocutory process dated 17 June 2026 be costs in the winding up of the Fund.
14 For the reasons that follow, I consider it appropriate to make directions and orders as sought by the Appointees. The reasons that follow are substantially based on the Appointees’ outlines of submissions.
Applicable principles
15 The applicable principles are set out in the December 2025 Reasons at [8]-[12]. I adopt that statement of the applicable principles.
Consideration
Summary of the Appointees’ submissions
16 The Appointees submit, in summary, that the proposed interim distribution is appropriate and justified for the following reasons. They submit:
(a) First, properly construed, the SMF Constitution permits the making of an interim distribution in the nature proposed.
(b) Second, many of the underlying investors in the SMF are individuals approaching retirement age with low superannuation balances and who invested high proportions of their total superannuation in the SMF. Superannuation is a legislated means for retirees to fund their living expenses in retirement. Investors have been prevented from redeeming their units in the SMF since February 2024, which has caused them significant hardship. The interim distribution will assist in alleviating that hardship.
(c) Third, if the interim distribution is not made, members of the SMF will not receive a dividend until the conclusion of the winding up of the SMF, which is expected to take several years. During that time, many underlying investors will be unable to access any of their superannuation invested in the SMF, such that their existing hardship will be amplified, defeating the purpose of superannuation as a means of funding living expenses in retirement.
(d) Fourth, the Appointees have provisioned to retain sufficient realisation proceeds to meet the claims of known SMF creditors, and the likely costs and expenses of the winding up and receivership of the SMF, which are required to be paid in priority to distributions to unitholders under the SMF Constitution. The Appointees have not retained a provision for potential creditors whom they have assessed as non-SMF creditors as those creditors are unlikely to have any entitlement to share in the proceeds realised from the Bell Potter Securities. The SMF Constitution confers a discretion on the responsible entity whether to retain funds to meet contingent liabilities. The Appointees have, however, provisioned for a $8 million contingency buffer to meet any unforeseen claims, costs or expenses.
(e) Fifth, no creditors or potentially affected parties have expressed any opposition to the proposed interim distribution.
Structure of the SMF
17 The SMF is a registered managed investment scheme, regulated under Chapter 5C of the Corporations Act 2001 (Cth), that was registered on or around 5 July 2021. Keystone was (and remains) the responsible entity for the SMF.
18 The interests in the SMF are described as units, and the members of the SMF are described as unitholders. There are five investment classes of units in the SMF (each, a Class), each with separate asset pools.
19 The SMF had invested funds in a number of different assets, including all the units in the Advantage Diversified Property Fund, the Bell Potter Securities and interests in illiquid funds. The Bell Potter Securities are the only asset of the SMF that could be (and have now been) readily liquidated in order to make an interim distribution in a meaningful amount for unitholders.
20 In accordance with the order made on 19 December 2025, the Appointees instructed Bell Potter to liquidate the Bell Potter Securities. The Bell Potter Securities have now been sold and the following proceeds of their realisation (the Bell Potter Proceeds) have been deposited in interest-bearing accounts for the respective Classes in the following amounts:
1. | Conservative Class | $29,811,886.42 |
2. | Balanced Class | $59,525,815.98 |
3. | Growth Class | $96,930,383.10 |
4. | High Growth Class | $9,622,879.21 |
5. | Advantage Diversified Property Class | $Nil |
Total | $195,890,964.71 |
Investors in the SMF
21 Until September 2025, the units in the SMF were held in the following ways:
(a) “directly” by individuals or self-managed superannuation funds;
(b) indirectly where units were held for underlying investors through their membership of superannuation funds and investor-director portfolio services operated by the following entities:
(i) MIML (with the units held by BSCL as custodian);
(ii) ETSL;
(iii) The Trust Company (PTAL) Ltd (TTCL); and
(iv) HSBC Custody Nominees (Australia) Limited (HCNL).
22 MIML’s clients indirectly invested in the SMF as members of either the Macquarie Superannuation Fund (MSF), a “platform” style superannuation fund, or an investor directed portfolio service (IDPS), of which MIML is the trustee and operator.
23 On 24 September 2025, MIML entered into an enforceable undertaking (EU) with ASIC. Under the EU, MIML committed to transactions in which the Macquarie Group would acquire the SMF units then held by MIML for the economic benefit of members of the MSF and IDPS who invested in the SMF. These transactions have now been effected, and the units registered to BSCL are now held as trustee or custodian for MFL.
24 The following table sets out the number of units in the SMF by unitholder and the Classes in which the relevant units are held based on the best available unit register information for the SMF:
25 BSCL and ETSL hold a significant majority of units in the SMF for the investment services they offered to underlying investors (although the units held by BSCL are now beneficially owned by MFL). BSCL and ETSL hold over 97% of units in the Conservative, Balanced, Growth and High Growth Classes of the SMF.
Termination and winding up of the SMF
26 On 10 April 2025, the Receivers terminated the SMF, with the effect that it is in the process of being wound up in accordance with the SMF Constitution and s 601NE of the Corporations Act.
27 In light of the complexity of the property of the SMF and its sub-funds, and the extent of the investigations and litigation required to recover that property, the Appointees estimate that the winding up of the SMF and completion of the receivership may take at least a further 2 to 3 years and up to 7 years. This means that if investors – save for those underlying investors who received payments in respect of their investment from MIML under the EU – were required to wait for the winding up to take its course before receiving any dividend, they would not receive any funds from the SMF for an extended period of time.
The SMF Constitution
28 The SMF Constitution contains provisions which are relevant to the winding up of the SMF. They include clauses 5.4, 5.5, 5.7 and 5.8 of the SMF Constitution, which relate to the rights of the respective Classes to the Bell Potter Securities, and provide as follows:
5.4 A Unit in the Trust confers on its holder an interest in the Class Assets corresponding to Units in that Class.
5.5 A Unit in the Trust does not confer on its holder an interest in Class Assets corresponding to Units of a different Class to that Unit.
…
5.7 The Responsible Entity may create and issue Units in the Trust with different rights and restrictions as set out in the terms of issue (Class). Subject to the terms of issue, each Unit confers on its holder identical rights to those conferred by each other Unit of that Class.
5.8 The Responsible Entity may divide issued Units in the Trust into different Classes.
29 Clause 21.6(c) and (d) sets out the manner of the application of SMF assets after termination of the SMF (i.e. in the winding up):
21.6 After the termination of the Trust, the Responsible Entity:
…
(c) must apply the Class Assets of each Class, or the proceeds from their realisation, to pay:
(i) any corresponding Class Expense; and
(ii) other Expenses (including Expenses associated with its remuneration, the remuneration of any Agent or Adviser employed in connection with the termination of the Trust and any other Expenses associated with the termination of the Trust) which the Responsible Entity reasonably determines are not referable to a specific Class and should be met from the Class Assets of that Class, in conjunction with the Class Assets of such other Classes (if any) as determined by the Responsible Entity;
(d) may, subject to Class rights, distribute the remaining Scheme Property or the net proceeds to Unitholders of the Trust in proportion to the number of Units of which they are the registered holder on the Termination Date, but the Responsible Entity may retain Scheme Property or their proceeds for contingent Expenses and liabilities.
30 “Expenses” are relevantly defined in clause 1.1 as “all expenses, costs, losses and liabilities of the Trust (whether paid or unpaid, actual or contingent, present or future) …”.
31 Clause 13 of the SMF Constitution relates to distributions of income and capital generally. Clauses 13.10 and 13.42 relevantly provide as follows:
13.10 The Responsible Entity may distribute or cause to be distributed any amount (capital or income) by way of cash or in specie at any time on a pro-rata basis to the Unitholders of a Class according to the number of Units held by each Unitholder of that Class as a proportion of all Units of that Class on issue as at a time determined by the Responsible Entity.
…
13.42 The rights of a Member under this clause 13 are subject to the rights, obligations and restrictions attaching to any particular Unit or the Class of Units which they hold.
32 The Appointees submit (and I accept) that, on the proper construction of the SMF Constitution, Keystone has the power to make an interim distribution of realisation proceeds to unitholders, subject to ensuring that the distribution does not interfere with the payment of Expenses – which may include trust creditors of the SMF and the Receivers’ remuneration and expenses – in accordance with clause 21.6 of the SMF Constitution. The way that Keystone would ensure that the distribution would not interfere with the payment of Expenses is by provisioning funds for the known Expenses identified by the Appointees (as identified below) from the Bell Potter Proceeds and carving them out from the proposed interim distribution. This would allow for the payment of actual “Expenses” in priority to any distributions to unitholders. The Appointees’ proposed approach to provisioning funds is also consistent with clause 21.6(d) of the SMF Constitution which, in respect of “contingent Expenses and liabilities”, confers on Keystone a discretion as to whether to retain realisation proceeds to satisfy such contingencies.
Purpose of proposed interim distribution
33 The purpose of the proposed distribution is to alleviate the hardship which many of the underlying investors are suffering following the suspension of distributions from the SMF since February 2024, and generally to make an interim distribution to unitholders as soon as possible. Many of the underlying investors in the SMF were individuals approaching retirement age with low superannuation balances and who invested high proportions of their total superannuation in the SMF. The cessation of redemptions and payments to unitholders of the SMF since February 2024 is likely to have caused significant hardship for some of those individuals who, either directly or indirectly through financial services offered by institutions, invested in the SMF. The Appointees have received communications from individual investors explaining their serious financial hardship.
34 Although for some underlying investors (those who invested in the SMF via MIML) their hardship has been alleviated as a result of the ex gratia payments made to them under the EU, the hardship considerations remain relevant with respect to underlying investors who invested via ETSL. Any interim distribution must be made commensurately to all unitholders; it is not possible to make interim distributions only to some unitholders but not others.
Reasons for seeking judicial advice
35 The dilemma facing the Appointees – and the impetus for approaching the Court in this application for directions and judicial advice – is that the interim distribution may create the risk of criticism by creditors of Keystone who might perceive that they would be adversely affected by the interim distribution.
36 The identified risks are addressed in paras 42-83 of the Appointees’ outline of submissions dated 29 January 2026.
Outstanding issues on 15 June 2026
37 As noted above, the materials filed for the purposes of the hearing on 15 June 2026 indicated that several issues relating to the proposed interim distribution remained unresolved. These issues related to the following topics:
(a) deed polls from unitholders of qualifying Classes;
(b) unitholder reconciliation and redemption claims; and
(c) taxation consequences of the proposed interim distribution.
38 These outstanding matters have now been addressed in Mr Tracy’s affidavit of 24 September 2026 and the Appointees’ outline of submissions dated 25 September 2026.
39 In relation to the deed polls issue, the Appointees have received deed polls from ETSL and the Macquarie Parties (which, upon the payment of the proposed interim distribution, operate to subordinate any claims of those parties to other provable claims of creditors in the liquidation of Keystone), but not from Praemium on behalf of HCNL and HSBC Bank Australia Limited. For the reasons set out in paras 5-8 of the Appointees’ outline of submissions dated 25 September 2026, I am satisfied with the way the Appointees propose to deal with this issue.
40 In relation to the issue of unitholder reconciliation and redemption claims, for the reasons set out in paras 9-18 of the Appointees’ outline of submissions dated 25 September 2026, I am satisfied with the way the Appointees propose to deal with this issue.
41 In relation to the taxation consequences of the proposed interim distribution, the Appointees’ proposed approach is outlined in paras 27-57 of the Appointees’ outline of submissions dated 25 September 2026. I am satisfied that it is open to the Appointees to approach the taxation issues in the way there outlined and do not have concerns with their proposed approach.
42 Since the hearing on 15 June 2026, the Appointees have revised the amounts of the provisions to be withheld from the proposed interim distribution for: (a) actual and forecast costs; (b) potential creditor claims; and (c) contingencies, based on updated information that has become available.
Updated details relating to proposed interim distribution
43 Mr Tracy’s affidavit dated 24 September 2026 contains a breakdown and explanation for the updated retention figures. In summary, the Appointees’ updated calculations of the proposed interim distribution amount provides for the following reserved amounts to be retained:
(a) payment of total currently invoiced (that is, actual) costs ($925,383.87);
(b) forecast costs ($58,435,862.95);
(c) creditor claims ($26,990,438.48); and
(d) contingency ($8,000,000.00),
totalling $94,351,685.30 (together, the Retained Amounts).
44 After subtracting the Retained Amounts from the cash at bank, the total estimated amount of the proposed interim distribution is $100,186,713.49.
45 Based on the Appointees’ updated calculations, it is anticipated that no amount will be paid from the proposed interim distribution to the High Growth Class because the allocation of the Retained Amounts to the High Growth Class ($14,356,469.41) exceeds the share of the cash available for distribution to the High Growth Class ($9,001,797.47). This matter was the subject of explanation at the hearing on 29 September 2026. I am satisfied with that explanation.
46 In the High Growth Class, on behalf of their respective underlying investors:
(a) the Macquarie Parties hold 61,132,871.02 units; and
(b) ETSL holds 4,357,877.60 NQ units (being units held by ETSL in its capacity as trustee of AMG Super (Freedom of Choice division)) and 5,219,111.39 TTCL units.
47 For this reason, the Appointees have made further adjustments to the assets available to the Conservative, Balanced and Growth Classes for the proposed interim distribution to cover any shortfall in respect of the share of invoiced and forecast costs, and reservations attributed to the High Growth Class. As addressed below, the Appointees have also considered the implication of the High Growth Class not receiving any interim distribution in the context of taxable income being attributed to the High Growth Class through the issuing of “AMMA Statements” for FY24 and FY25.
48 The estimated amount of the proposed interim distribution for each of the qualifying Classes is proposed to be as follows:
Qualifying Class | Per qualifying Class | Per unit in each qualifying Class |
Conservative | $16,397,901.65 | $0.28 |
Balanced | $34,325,141.50 | $0.31 |
Growth | $49,463,670.33 | $0.25 |
High Growth | $0.00 | $0.00 |
Total | $100,186,713.49 | NA |
Overall consideration
49 Having regard to the facts and matters set out above, I consider that the proposed interim distribution is an appropriate step to be undertaken to alleviate the hardship of some of the underlying investors. While that rationale does not apply in relation to the Macquarie Parties, I accept the Appointees’ submission that any distribution needs to be effected equally across unitholders. Therefore, to address the hardship of the other underlying investors, it is necessary to include the Macquarie Parties in the proposed interim distribution. Accordingly, I consider it appropriate to give a direction and make orders as sought in paras 1 and 2 of the proposed orders.
50 In relation to para 3 of the proposed orders, for the reasons set out in paras 21-27 of the Appointees’ outline of submissions dated 31 May 2026, I consider it appropriate to make this order.
Conclusion
51 I will therefore make orders substantially as sought by the Appointees.
I certify that the preceding fifty-one (51) numbered paragraphs are a true copy of the Reasons for Judgment of the Honourable Justice Moshinsky. |
Associate:
Dated: 6 October 2026